Home loan balance transfer 2026 is the single most important financial move thousands of Indian borrowers should be making right now. With home loan balance transfer rates dropping to as low as 7.10% p.a. in 2026, and many borrowers still paying 8.5–9.5% on loans taken between 2018 and 2023, the savings opportunity is enormous. As a 14-year senior banking professional, I have helped hundreds of families execute a successful home loan balance transfer in 2026 — and in this complete guide I will tell you exactly which banks offer the best rates, how much you can save, when it is worth doing, and when it is absolutely not.
A home loan balance transfer is one of the smartest financial decisions for existing borrowers paying above 8.5% interest. With balance transfer rates now as low as 7.10% p.a. from PSU banks, the home loan balance transfer window is wide open — especially for borrowers who took loans between 2018 and 2022 when rates were significantly higher. Whether you are evaluating a home loan balance transfer from SBI, HDFC, ICICI, or any other lender, this complete balance transfer guide covers everything you need to make the right decision — including the one banker’s secret that could save you the entire cost of transferring.
Balance transfer — Interest Rates, Savings & Complete Process

Free tool
Check what a switch could save with the balance transfer calculator, and your new instalment with the Loan EMI calculator.
Estimates only. Check current terms with your bank before you decide.
Balance Transfer Rates: Top 20 Banks Compared
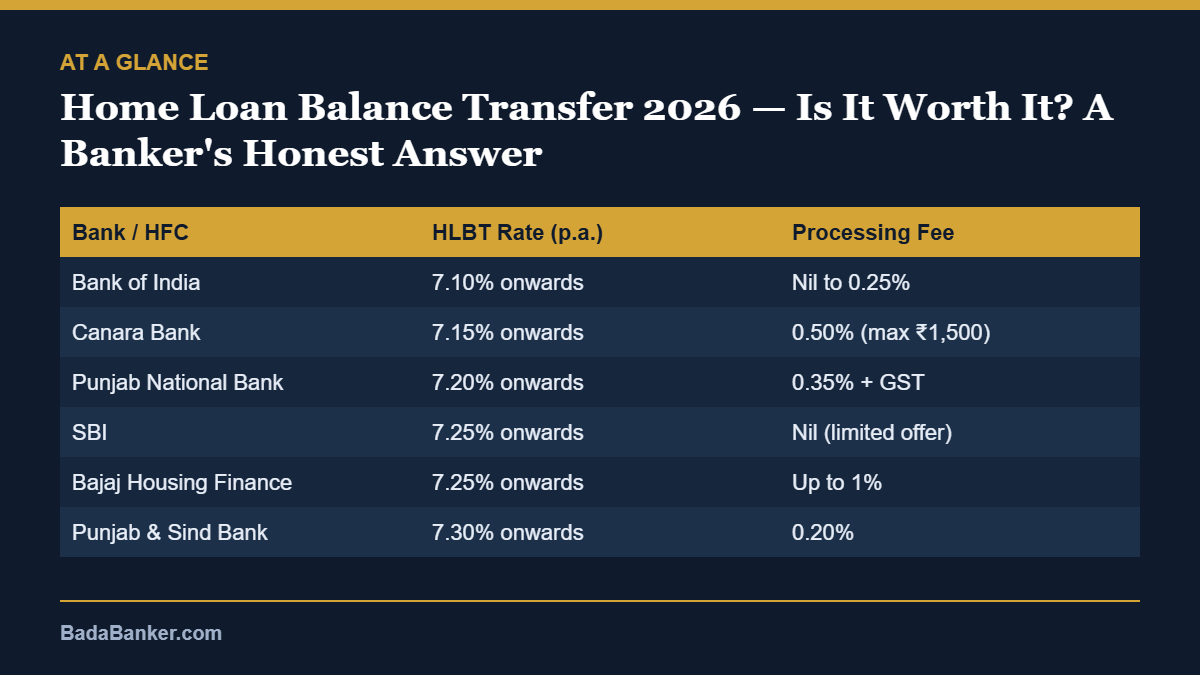
Here is the most current balance transferterest rate comparison across all major banks and HFCs in India as of May 2026. The balance transfer rates have dropped significantly compared to last year — PSU banks are leading with the lowest rates.
| Bank / HFC | HLBT Rate (p.a.) | Processing Fee | Banker’s Rating |
|---|---|---|---|
| Bank of India | 7.10% onwards | Nil to 0.25% | ⭐ Best Rate 2026 |
| Canara Bank | 7.15% onwards | 0.50% (max ₹1,500) | ⭐ Lowest Cost |
| Punjab National Bank | 7.20% onwards | 0.35% + GST | Excellent |
| SBI | 7.25% onwards | Nil (limited offer) | Most Trusted |
| Bajaj Housing Finance | 7.25% onwards | Up to 1% | Fastest Process |
| Punjab & Sind Bank | 7.30% onwards | 0.20% | Good |
| IDBI Bank | 7.35% onwards | 0.50% | Good |
| HDFC Bank | 7.45% onwards | Up to 0.50% | Good |
| Kotak Mahindra Bank | 7.45% onwards | 0.50% | Good |
| LIC Housing Finance | 7.50% onwards | Up to 0.50% | Good |
| PNB Housing Finance | 7.70% onwards | Up to 0.50% | Average |
| Godrej Housing Finance | 7.75% onwards | Up to 1% | Average |
| Home First Finance | 8.00% onwards | Up to 1.5% | Average |
| ICICI Bank | 8.10% onwards | 0.50% + GST | Average |
| L&T Finance | 8.15% onwards | Up to 0.50% | Average |
| RBL Bank | 8.20% onwards | 1% + GST | Average |
| Axis Bank | 8.35% onwards | 1% + GST | Higher Rate |
| Federal Bank | 8.75% onwards | 0.50% | Higher Rate |
| IDFC FIRST Bank | 8.85% onwards | Up to 1.5% | Higher Rate |
| Piramal Capital HFC | 9.99% onwards | Up to 2% | Avoid for Transfer |
Balance transfer rates as of May 2026. Final rate depends on CIBIL score, loan amount, and employment type. Verify directly with bank before applying.
How Much Can You Save by Switching?
The home loan balance transfer savings can be substantial even with a modest rate reduction. Here is a real example with actual numbers showing exactly how much you save:
Example: Switching a ₹50 Lakh Home Loan
When Is a Balance Transfer Worth It?
Go ahead if:
- Your current rate is 0.5% or more above the best available rate
- You have at least 10 years remaining on your loan tenure
- Your CIBIL score has improved to 750+ since you took the original loan
- Your lender is charging above 8.5% on a floating rate in 2026
- The new lender offers a top-up loan you also need
Skip it if:
- You have less than 5 years remaining — most interest already paid
- Rate difference is less than 0.5% — fees will eat the savings
- Your CIBIL score is below 700 — you won’t get best rates
- You plan to sell the property within 2–3 years
- Your existing lender can match the rate through negotiation
Do’s and Don’ts
Do This
- Compare at least 5 banks before deciding
- Calculate total cost including all fees
- Negotiate with existing lender first
- Check if top-up loan is available
- Maintain CIBIL score above 750
- Transfer early in the loan tenure
- Read the new loan agreement carefully
Avoid This
- Transfer without calculating processing costs
- Transfer in last 5 years of tenure
- Go to a lender without verifying RBI licence
- Skip reading the foreclosure clause
- Transfer for less than 0.5% rate benefit
- Ignore the new lender’s service quality
- Transfer multiple times in short gaps
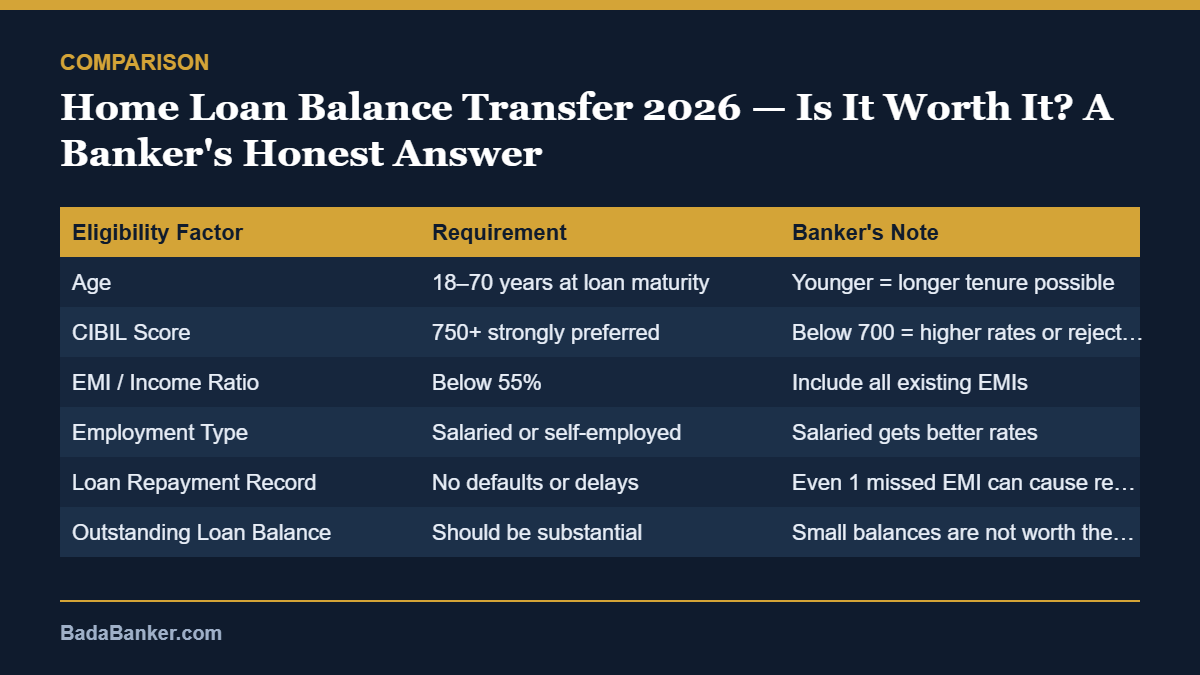
Eligibility Criteria
| Eligibility Factor | Requirement | Banker’s Note |
|---|---|---|
| Age | 18–70 years at loan maturity | Younger = longer tenure possible |
| CIBIL Score | 750+ strongly preferred | Below 700 = higher rates or rejection |
| EMI / Income Ratio | Below 55% | Include all existing EMIs |
| Employment Type | Salaried or self-employed | Salaried gets better rates |
| Loan Repayment Record | No defaults or delays | Even 1 missed EMI can cause rejection |
| Outstanding Loan Balance | Should be substantial | Small balances are not worth the cost |
| Property Status | Clear title, no legal dispute | New lender will re-verify property |
Documents Required
KYC Documents
- PAN Card
- Aadhaar Card
- Passport / Voter ID / Driving Licence (any one)
- 2 passport-size photographs
Income Documents — Salaried Applicants
- Last 3 months salary slips
- Last 6 months bank statements
- Form 16 / ITR for last 2 years
- Employment / appointment letter
Income Documents — Self-Employed Applicants
- ITR for last 3 years with CA acknowledgement
- Audited balance sheet and P&L for last 2 years
- Last 12 months business bank statements
- Business registration / GST certificate
Property & Loan Documents
- Original sale deed / title deed
- NOC from existing lender
- Foreclosure letter from existing lender
- Last 12 months loan repayment statement
- Approved building plan / occupancy certificate
Step-by-Step Process
Compare rates from at least five lenders
Use the rate table above. Focus on PSU banks first — they offer the lowest balance transfer rates. Get written rate quotes, not verbal promises.
Negotiate with your existing lender before transferring
Call your bank and tell them you have a better balance transfer offer. Ask for a rate reduction. If they match — stay. If not — proceed with the transfer.
Apply to the new lender and get approval
Submit your application with all documents. The new lender verifies income, CIBIL score, and property. Processing takes 7–15 working days typically.
Collect NOC and foreclosure letter from existing lender
Once new lender approves, apply to existing bank for foreclosure letter and NOC. This is the slowest step in the home loan balance transfer process — start early.
New lender pays existing lender and takes over
The new lender pays the outstanding amount directly to your existing bank. You get a new loan agreement with the new interest rate. EMI changes from next billing cycle.
Collect all original property documents
After full repayment, collect ALL original documents from your old lender. Never leave originals with a lender whose loan is fully closed.
SBI vs HDFC vs ICICI Compared
| Parameter | SBI | HDFC Bank | ICICI Bank |
|---|---|---|---|
| HLBT Starting Rate 2026 | 7.25% | 7.45% | 8.10% |
| Processing Fee | Nil (current offer) | Up to 0.50% | 0.50% + GST |
| Foreclosure Charge | Nil (floating rate) | Nil (floating rate) | Nil (floating rate) |
| Top-Up Loan Available | Yes | Yes | Yes |
| Minimum CIBIL Score | 700+ | 750+ | 750+ |
| Processing Time | 10–15 days | 7–10 days | 7–10 days |
| Banker’s Pick for HLBT 2026 | Best for large loans | Best for speed | Only if CIBIL 780+ |
“A home loan balance transfer is genuinely worth it if your current rate is above 8.5% and you have 10+ years remaining. PSU banks — Bank of India, Canara Bank, SBI — are offering the best balance transfer rates in 2026, starting from just 7.10–7.25%. But before you transfer, call your existing bank first and ask for a rate reduction. I have seen banks reduce rates by 0.3–0.5% simply because the borrower asked. That call costs you nothing. The home loan balance transfer process costs ₹30,000–₹70,000 in fees. Make the free call first.”
Frequently Asked Questions
Want to Know If Home Loan Balance Transfer Is Worth It for You?
Our banking experts calculate your exact savings from a balance transfer, compare rates from 20+ banks, and give you an honest recommendation — completely free, no obligation.
📎 Sources:
RBI Home Loan Guidelines ·
Bank Rate Data May 2026 ·
Individual bank websites verified May 2026.
Balance transfer rates are indicative and subject to change. Always verify with the bank directly before applying. This is not financial advice — consult a qualified advisor before making loan decisions.