TDS on FD interest in 2026 works on two rules every fixed deposit holder in India should know: banks deduct TDS only when your interest from one bank crosses ₹50,000 a year, or ₹1 lakh for senior citizens, and from 1 April 2026 the familiar Forms 15G and 15H have been replaced by a single Form 121.
Understanding TDS on FD interest 2026 rules correctly can save you thousands in unnecessary tax deductions — and avoid the hassle of claiming refunds while filing your ITR. This complete guide explains the TDS on FD interest 2026 rules in plain language — who it applies to, how much gets deducted, how to avoid TDS legally, and the step-by-step process for submitting the new Form 121.
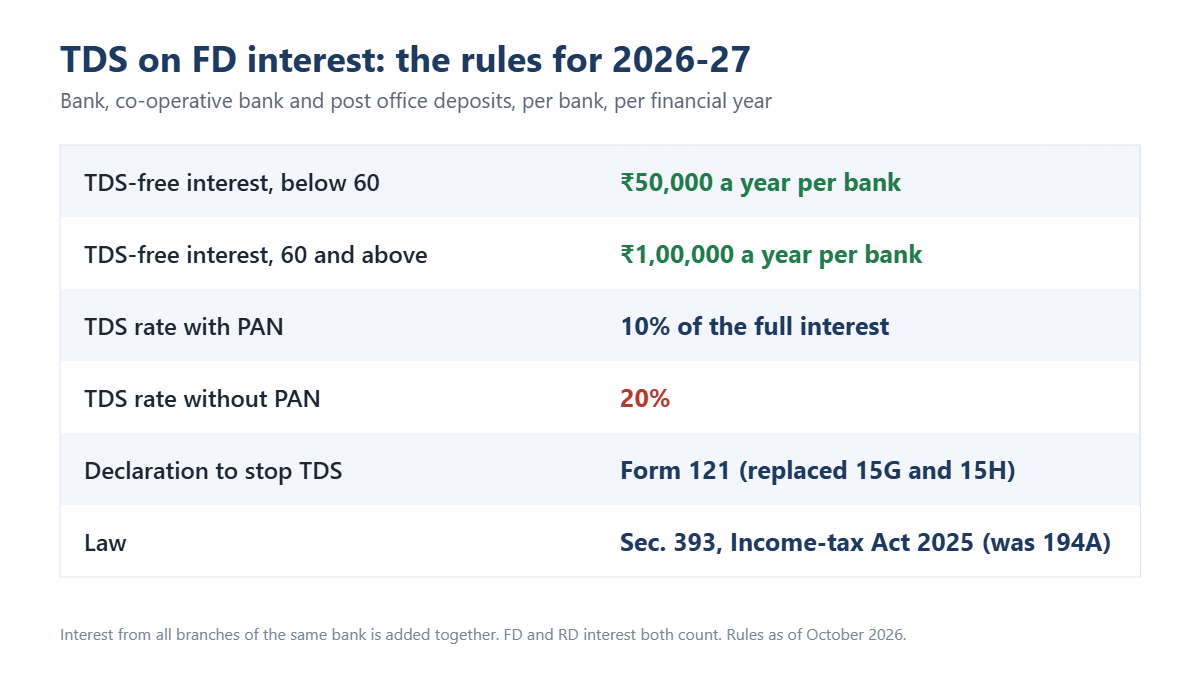
From 1 April 2026, TDS on FD interest falls under Section 393 of the Income-tax Act, 2025, which replaced the 1961 Act (earlier, Section 194A). The thresholds were raised by the Finance Act, 2025 from 1 April 2025 and carry over to the new Act: ₹50,000 a year for depositors below 60 (up from ₹40,000) and ₹1 lakh for senior citizens (up from ₹50,000). The rate is 10% if the bank has your PAN and 20% if it does not. Form 121, a single self-declaration for all ages, lets eligible depositors stop TDS at source instead of claiming a refund later.

- TDS threshold raised from April 1, 2025: General citizens — ₹50,000 per year (was ₹40,000). Senior citizens (60+) — ₹1,00,000 per year (was ₹50,000). TDS is deducted only if your annual FD interest exceeds these limits.
- TDS rate is 10% if PAN is provided. If PAN is not linked to your FD — rate jumps to 20%. Always ensure PAN is updated with your bank.
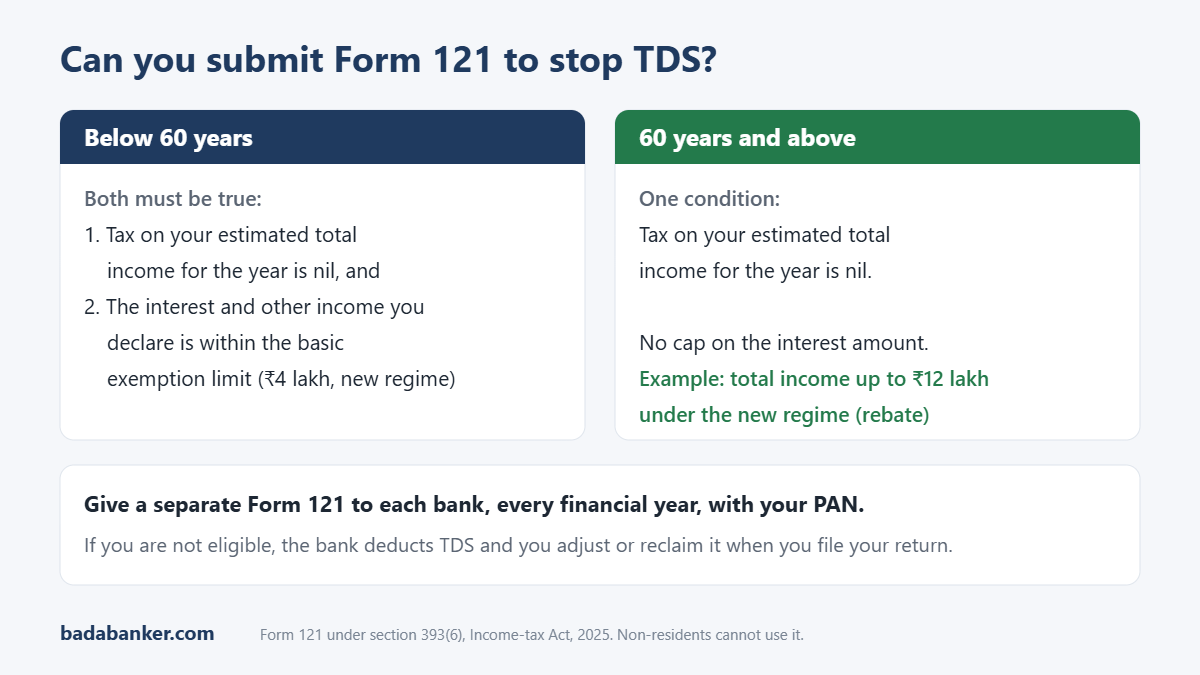
- Form 121 replaces Form 15G and 15H from April 1, 2026. One unified form for all eligible depositors to prevent TDS deduction if total income is below the taxable limit.
- TDS is calculated across all branches of the same bank — not per branch. CBS (Core Banking System) aggregates all FD interest from all branches together before applying the threshold.
- TDS deducted is not final tax. It is only an advance deduction. You can claim full refund while filing ITR if your total income is below the taxable limit.
Every year, millions of Indian FD holders are surprised when they see TDS deducted from their interest — often because they were unaware of the threshold or forgot to submit the right form. With the higher thresholds and the new Form 121, understanding TDS correctly can save you real money and hours of refund paperwork.
Free tool
Estimate the interest on your deposit with the fixed deposit maturity calculator.
Estimates only. Check current terms with your bank before you decide.
What Changed: Old vs New Rules
| Rule | Before April 2025 (Old) | From April 2025 (New 2026) |
|---|---|---|
| TDS threshold — General citizens (below 60) | ₹40,000/year | ₹50,000/year |
| TDS threshold — Senior citizens (60+) | ₹50,000/year | ₹1,00,000/year |
| TDS rate (PAN provided) | 10% | 10% (unchanged) |
| TDS rate (no PAN) | 20% | 20% (unchanged) |
| Self-declaration form | Form 15G (general) / Form 15H (senior) | Form 121 (unified — from April 1, 2026) |
| Form validity | 1 financial year | 1 financial year (same) |
| Calculation method | All branches of same bank combined | All branches of same bank combined (same) |
How TDS Is Calculated: Worked Examples
Example 1 — General Citizen (Below 60)
| Scenario | Annual FD Interest | TDS Deducted | Reason |
|---|---|---|---|
| Ravi, 35 years, PAN linked | ₹45,000 | ₹0 | Below ₹50,000 threshold — no TDS |
| Priya, 42 years, PAN linked | ₹75,000 | ₹7,500 (10%) | Exceeds ₹50,000 — 10% on full ₹75,000 |
| Amit, 38 years, NO PAN | ₹55,000 | ₹11,000 (20%) | No PAN — 20% rate applies |
Example 2 — Senior Citizen (60+)
| Scenario | Annual FD Interest | TDS Deducted | Reason |
|---|---|---|---|
| Mrs. Sharma, 65 years, PAN linked | ₹90,000 | ₹0 | Below ₹1 lakh threshold — no TDS |
| Mr. Gupta, 68 years, PAN linked | ₹1,50,000 | ₹15,000 (10%) | Exceeds ₹1 lakh — 10% on full ₹1.5L |
| Mrs. Patel, 72 years, NO PAN | ₹1,10,000 | ₹22,000 (20%) | No PAN — 20% regardless of age |
TDS Calculator
Calculate Your TDS
Based on TDS rules for FY 2026–27 (Section 393, Income-tax Act, 2025)
New Form 121 — Replaces Form 15G and 15H from April 1, 2026
This is the most important change in TDS that most people have not heard about yet. The Income Tax Department has introduced Form 121 — a single unified self-declaration form that replaces both Form 15G (for general citizens) and Form 15H (for senior citizens).
| Feature | Old System (till March 2026) | New Form 121 (from April 2026) |
|---|---|---|
| Who submits which form | 15G for under 60 / 15H for 60+ | Single Form 121 for everyone |
| Purpose | Prevent TDS if income below taxable limit | Same purpose — prevent TDS deduction |
| Eligibility, below 60 | Tax on total income nil, and declared income within the basic exemption limit | Same conditions |
| Eligibility, 60 and above | Tax on total income nil | Same condition |
| Where to submit | To each bank or payer | To each bank or payer (branch, or online where the bank offers it) |
| When to submit | Start of financial year | Start of financial year (same) |
| Valid for | 1 financial year | 1 financial year (same) |
Who Should Submit Form 121
| Your Situation | Should You Submit Form 121? | Benefit |
|---|---|---|
| Below 60, new tax regime: total income up to ₹12 lakh (tax nil after rebate) and interest declared within ₹4 lakh | ✅ Yes | No TDS deducted during the year |
| Below 60, old tax regime: tax nil (total income up to ₹5 lakh, after the rebate) and interest declared within ₹2.5 lakh | ✅ Yes | No TDS deducted during the year |
| Senior citizen whose tax for the year will be nil (for example, total income up to ₹12 lakh under the new regime) | ✅ Yes | No TDS, no refund to chase |
| Any tax payable for the year, even at 5% | ❌ No — not eligible | TDS deducted — claim in ITR |
| Income in 20% or 30% slab | ❌ No — not eligible | TDS is advance tax — no refund |
| Housewife / retired with only FD income | ✅ Likely eligible | Calculate total income first |
How to Submit Form 121 to Your Bank — Step by Step
Get Form 121
Ask your bank for Form 121, or download it from the forms section of the Income Tax Department’s website (incometaxindia.gov.in). It replaced Forms 15G and 15H from 1 April 2026.
Fill in your details carefully
Name, PAN, address, financial year, estimated total income from all sources. Your estimated FD interest income. Your declaration that the tax on your estimated total income will be nil. Your PAN is compulsory. Sign the form, or verify it through the bank’s online process.
Submit it to each bank
Give the form to every bank where you hold FDs or RDs. Check whether your bank accepts it through net banking; otherwise submit it at the branch and keep the acknowledgement. Each bank needs its own form.
Submit at the start of every financial year
Form 121 is valid for only one financial year. Submit every April — before your bank processes the first quarter’s FD interest. If you miss it, TDS will be deducted and you will need to claim a refund in your ITR.
Check Form 26AS or your AIS
After submission, check Form 26AS or your Annual Information Statement (AIS) on the income tax e-filing portal to confirm that no TDS has been deducted on your FD interest.
Strategies to Manage TDS on Your FDs
If your FD interest is close to the threshold, here are legal strategies to manage TDS:
Strategy 1 — Split FDs Across Different Banks
TDS threshold applies bank-wise — not across all banks. If you have ₹90,000 annual FD interest, splitting it as ₹45,000 from SBI and ₹45,000 from HDFC means neither bank crosses the ₹50,000 threshold — resulting in zero TDS from both. This is completely legal.
Strategy 2 — Deposits in a family member’s own name
Each person’s threshold is counted separately, so a parent or adult child who holds FDs from their own money has their own ₹50,000 or ₹1 lakh limit. But be careful with gifts: if you give money to your spouse and it is invested in their name, the interest is generally added to your income under the clubbing rules. Gifts to parents or adult children are not clubbed.
Strategy 3 — Know that cumulative FDs do not delay TDS
A cumulative FD pays interest only at maturity, but banks still deduct TDS every financial year on the interest that accrues. Spreading maturities across years does not avoid TDS. What counts is the interest that accrues at that bank in each financial year.
“The TDS changes are genuinely positive for small depositors and senior citizens. The ₹1 lakh threshold for senior citizens means most retired individuals with moderate FD portfolios will see zero TDS deducted — a significant improvement. The new Form 121 replacing 15G and 15H simplifies compliance. The one action every FD holder should take right now: check if you are eligible for Form 121 and submit it at the start of every financial year. It takes 10 minutes and saves you the hassle of claiming a refund in ITR.”
Frequently Asked Questions
Confused About TDS on Your FD Interest?
Ask us your specific TDS question — we will tell you exactly whether you need to submit Form 121 and how much TDS you should expect on your FD portfolio.
📎 Sources:
Income Tax Department — Form No. 121 (declaration under section 393(6)) ·
Income Tax Department — Income-tax Act, 2025 ·
Business Standard — Budget 2025 TDS threshold increase.
For informational purposes only. Consult a CA or tax advisor for your specific situation.
Thanks for breaking down the new thresholds so clearly — I had not realised TDS is charged on the full interest once it crosses Rs 50,000, not just the excess. The point about Form 121 replacing Forms 15G and 15H from April 2026 is especially useful, and I will check whether I need to file it at the start of the financial year. The reminder that interest is aggregated across all branches of the same bank is a detail many FD holders would otherwise miss.