PPF, ELSS and NPS are the three long-term savings options most salaried people compare at tax time. None of them is best for everyone. The right choice depends on how long you can stay invested, how much risk you can take, and whether you use the old or the new tax regime. This guide compares them side by side, with worked numbers.
Free tool
Compare outcomes with the monthly investment calculator and the retirement corpus calculator.
Estimates only. Check current terms with your bank before you decide.
Quick Fact Check — NPS vs PPF vs ELSS 2026
- PPF: Government-notified interest rate, reviewed periodically; eligible interest and maturity proceeds are tax-exempt, 15-year lock-in, old-regime-only 80C deduction.
- ELSS: Market-linked, with no assured return, shortest lock-in among tax savers at 3 years, old-regime-only 80C deduction, LTCG taxed at 12.5% above ₹1.25 lakh gains.
- NPS: Market-linked retirement savings. Personal contributions and employer contributions have different tax treatment. The extra personal-contribution deduction of up to ₹50,000, commonly referenced as Section 80CCD(1B), is an old-regime benefit. Employer contributions, commonly referenced as Section 80CCD(2), can qualify under the new regime, subject to the applicable salary percentage and other limits. For a non-government employee the percentage is 14% in the new regime, versus 10% in the old regime; government employer contributions have a 14% limit.
7.1%
PPF rate for October–December 2026
3 Years
ELSS lock-in — shortest of the three
New Regime OK
NPS employer contribution deduction survives
15 Years
PPF lock-in

The One That Works Even on the New Regime
This is the detail most people miss: while PPF and ELSS deductions require the old regime, NPS’s employer contribution deduction under Section 80CCD(2) is available even if you’re on the new regime. If your employer offers NPS as part of your salary structure, check the eligible deduction with payroll; an employer contribution may form part of your total compensation rather than being extra free money.

Worked example 1: how much tax NPS vs PPF vs ELSS saves
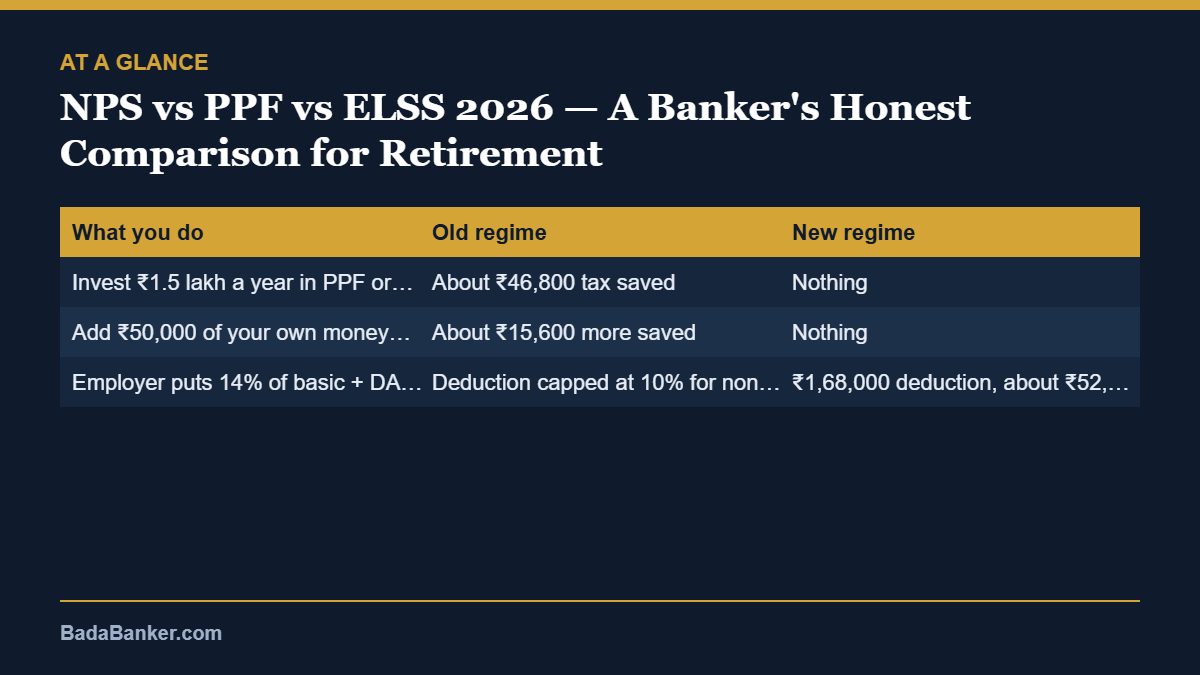
Take a salaried person in the 30% slab. With 4% cess, each ₹1 of deduction saves about 31.2 paise.
| What you do | Old regime | New regime |
|---|---|---|
| Invest ₹1.5 lakh a year in PPF or ELSS (80C) | About ₹46,800 tax saved | Nothing |
| Add ₹50,000 of your own money to NPS (80CCD(1B)) | About ₹15,600 more saved | Nothing |
| Employer puts 14% of basic + DA in NPS, on ₹1 lakh a month basic + DA (80CCD(2)) | Deduction capped at 10% for non-government employers | ₹1,68,000 deduction, about ₹52,400 tax saved |
The last row is why NPS stands out for people on the new regime. Ask your employer whether it offers NPS through the salary structure. It usually means restructuring part of your pay rather than getting extra money.
Worked example 2: ₹1.5 lakh a year for 15 years
Suppose you invest ₹1.5 lakh at the start of every year for 15 years, ₹22.5 lakh in total. PPF uses its current 7.1% rate, assuming it stays the same. ELSS returns are not assured, so we show three assumed returns.

| Option | Value after 15 years | Tax on the gain |
|---|---|---|
| PPF at 7.1% | about ₹40.7 lakh | None (exempt) |
| ELSS at an assumed 8% a year | about ₹44.0 lakh | about ₹2.6 lakh if all redeemed in one year |
| ELSS at an assumed 10% a year | about ₹52.4 lakh | about ₹3.7 lakh if all redeemed in one year |
| ELSS at an assumed 12% a year | about ₹62.6 lakh | higher, at 12.5% plus cess on gains above ₹1.25 lakh |
At an 8% return, ELSS ends up at about ₹41.4 lakh after tax, almost the same as PPF, but with market risk along the way. ELSS pulls ahead only if equity returns are meaningfully higher than the PPF rate. Spreading redemptions over several years, so each year’s gain stays near the ₹1.25 lakh exemption, reduces the tax. NPS can’t be compared directly here: at retirement, part of the corpus must buy an annuity, as explained below.
NPS vs PPF vs ELSS: Which Suits Which Goal
Archana’s Tip: PPF suits someone who wants government-backed savings with a notified rate, while still considering inflation and access restrictions and doesn’t mind locking money away for 15 years — ideal alongside other investments, not as your only one. ELSS suits someone comfortable with market risk who wants the shortest lock-in among tax-saving options. NPS suits long-term retirement planning specifically, especially if your employer contributes, but remember it has restrictions on withdrawal before retirement that PPF and ELSS don’t.
The NPS vs PPF vs ELSS Rules People Get Wrong
PPF partial withdrawal: allowed from the 7th financial year onward, capped at 50% of the balance at the end of the 4th year (or the immediately preceding year, whichever is lower) — not the full balance.
PPF after 15 years: you can extend in blocks of 5 years, either with fresh contributions (retaining 80C eligibility) or without — most people don’t realize the account doesn’t have to close at 15 years.
ELSS lock-in is per-installment: if you invest via SIP, each monthly installment has its own separate 3-year lock-in from its investment date — not one lock-in for the whole SIP.
NPS Tier 2: a voluntary, no-lock-in NPS account exists alongside the mandatory Tier 1, but it carries no tax benefit under 80C (except for government employees) — don’t confuse it with Tier 1’s tax advantages.
Common NPS vs PPF vs ELSS Mistakes
Mistake 1 — Assuming ELSS units must be sold the day the 3-year lock-in ends (you can hold as long as you like). Mistake 2 — Maxing out 80C via PPF/ELSS/insurance and forgetting the separate ₹50,000 NPS-only deduction under 80CCD(1B) exists on top under the old regime, subject to eligibility. Mistake 3 — Not checking whether your employer already offers NPS under 80CCD(2) before assuming you’d need to invest personally to get that benefit.
Our Verdict on NPS vs PPF vs ELSS
📋 Our Verdict — NPS vs PPF vs ELSS 2026
“Don’t pick just one — for most people, a mix works best: PPF for guaranteed long-term safety, ELSS for growth with a shorter commitment, and NPS specifically for retirement, especially if your employer contributes. On the new tax regime, NPS’s 80CCD(2) benefit is the one deduction still worth actively using.”
NPS vs PPF vs ELSS — FAQs
Q: Can I invest in all three simultaneously?
A: Yes, and many financially disciplined people do — they serve different purposes (safety, growth, retirement) rather than competing for the same money.
Q: Is NPS withdrawal fully tax-free at retirement?
A: Do not apply a universal 60%/40% rule. PFRDA’s current normal-exit rules for the non-government All Citizen model can permit up to 80% lump sum with at least 20% annuity; smaller-corpus options and other exit categories differ. Permission to withdraw is separate from income-tax exemption. Check both your applicable PFRDA exit category and the tax treatment before selecting a payout; annuity income is generally taxable.
Q: Can I open a PPF account for my minor child?
A: Yes, but the combined contribution limit across the guardian’s own and the minor’s account is still ₹1.5 lakh/year total for 80C purposes.
Q: Is ELSS better than a regular equity mutual fund?
A: Only for the tax deduction — post-tax returns depend on fund performance like any equity fund; don’t choose ELSS purely for “safety,” it carries full market risk.
Browse more tax regime comparison and Tax & Compliance coverage on BadaBanker.
Official references
Income Tax Department: deductions · PFRDA: NPS All Citizen model and exit rules.
Tax section labels above are the familiar 1961 Act references used in the linked deduction guidance. Check the applicable tax year and corresponding provisions under the Income-tax Act, 2025 when filing. Educational comparison only; consult a qualified adviser for your circumstances.
Compare NPS vs PPF vs ELSS against your own goal and time horizon, and check the latest tax rules before you invest.
The new-regime point about NPS employer contributions was the eye-opener for me — I had assumed all three options lost their tax benefit under the new regime. Your 15-year worked example also makes the trade-off concrete, showing ELSS and PPF ending up close after tax at an 8% return despite very different risks. I agree with the verdict that a mix, rather than picking just one, makes the most sense for most savers.