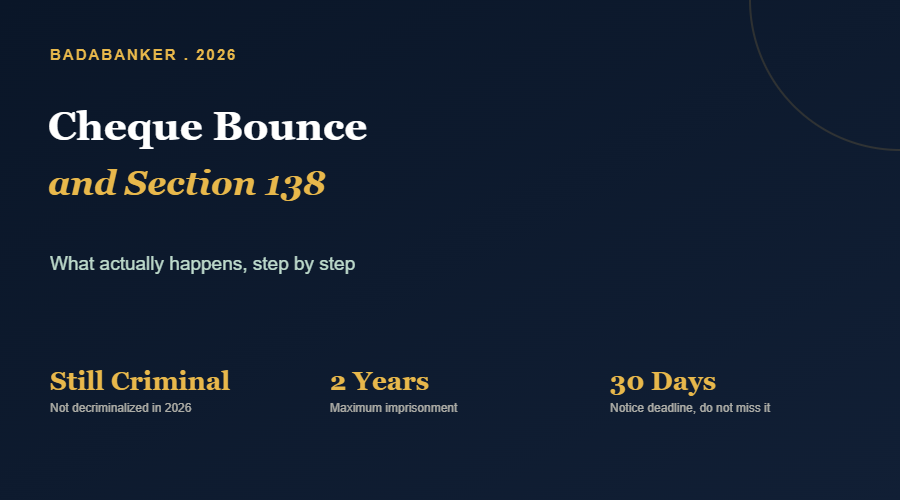
I still hear people say “cheque bounce ab decriminalize ho gaya hai” — it hasn’t. Despite a government proposal floated back in 2020, Section 138 of the Negotiable Instruments Act remains a criminal offence in 2026. Here’s exactly what happens, step by step, if a cheque bounces.
Quick Fact Check — Cheque Bounce 2026
- Still a criminal offence: Despite years of decriminalization proposals, Section 138 has NOT been decriminalized as of 2026 — it remains a non-cognizable, bailable criminal offence.
- Punishment: Up to 2 years imprisonment, a fine up to twice the cheque amount, or both.
- You must act within strict timelines — miss them, and you lose your right to prosecute under Section 138 (though a civil recovery suit may still be possible).
Criminal Offence
Not decriminalized, despite 2020 proposal
2 Years
Maximum imprisonment
2x Cheque Value
Maximum fine
Strict Timelines
Miss them, lose your Section 138 remedy
The Step-by-Step Process
1. Cheque Returns Unpaid
Your bank returns the cheque with a memo stating the reason — most commonly “insufficient funds” or “account closed.”
2. Send a Legal Demand Notice — Within 30 Days
You must send a written notice to the drawer demanding payment, within 30 days of receiving the bank’s return memo. This step is mandatory — skipping it invalidates your case.
3. Drawer Gets 15 Days to Pay
If the drawer pays within 15 days of receiving your notice, the matter ends there — no offence is deemed to have occurred.
4. File a Complaint — Within 30 Days of the 15-Day Window Expiring
If payment isn’t made, you can file a criminal complaint in the appropriate Magistrate’s court within 30 days after the 15-day payment window lapses.
Archana’s Tip: Miss the 30-day notice window or the 30-day complaint window, and you generally lose your Section 138 remedy entirely — courts are strict about these timelines. Act immediately once a cheque bounces; don’t wait, hoping the person will pay eventually.
Our Verdict
📋 Our Verdict — Cheque Bounce 2026
“Section 138 remains a real, criminal deterrent in 2026 — don’t let anyone tell you otherwise. But its power depends entirely on you following the timelines exactly. The moment a cheque bounces, calendar your 30-day notice deadline immediately.”
Cheque Bounce — FAQs
Q: Can I settle out of court after filing a complaint?
A: Yes, Section 138 cases are frequently compounded (settled) at any stage, including after filing, if both parties agree.
Q: Is a bounced cheque always intentional fraud?
A: No — Section 138 applies regardless of intent, as long as the cheque was for a legally enforceable debt and bounced due to insufficient funds or similar reasons.
Browse more Loans and legal finance coverage on BadaBanker.
📎 Sources: Negotiable Instruments Act, 1881, Section 138; publicly reported status of decriminalization proposals as of 2026. For informational purposes only — consult a lawyer for your specific situation.