15-Minute Gold Loan 2026: Is It a Trap? Full Guide
15-Minute Gold Loan 2026 offers are everywhere right now — banners promising cash against your gold in 15 minutes, no income proof, no CIBIL check. When a medical emergency hits or a business payment is due tomorrow, that banner feels like a lifeline. It usually is a legal, RBI-regulated product. But the 15-Minute Gold Loan 2026 pitch is also frequently wrapped in marketing that hides the real cost behind the speed. Here’s what actually happens between the ad and the cash hitting your account.
I want to be clear upfront: a 15-Minute Gold Loan 2026 from a registered NBFC or bank is not a scam. It’s a legitimate, fast-moving product built on physical collateral — your gold — which is exactly why it can be disbursed so quickly. The problem isn’t legality. It’s what gets left out of the advertisement.
Quick Fact Check — 15-Minute Gold Loan 2026
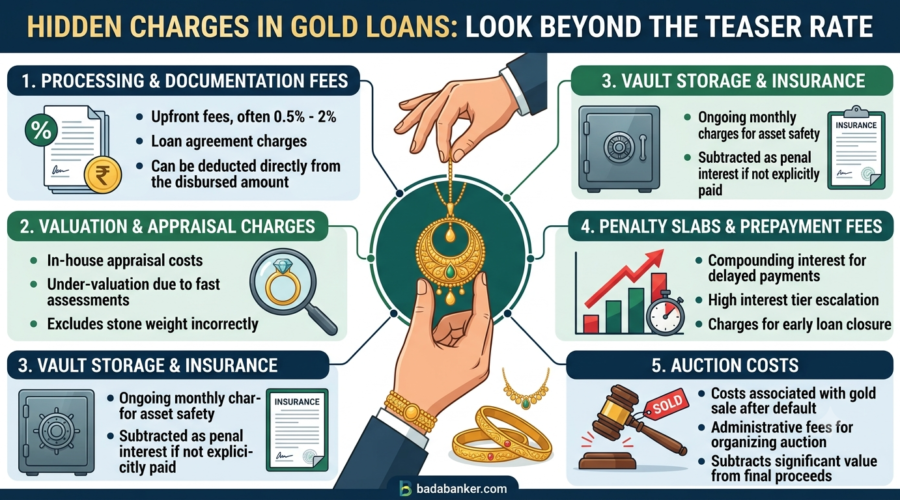
- Teaser rates: advertised rates as low as 0.99% per month (~11.88% p.a.) are often introductory — miss one payment and the loan can jump to 24-36% APR with compounding penalties.
- Purity haircuts: rapid 15-minute assays often value 22-karat gold closer to 18-karat, meaning you get less cash than your gold is actually worth.
- Upfront deductions: processing fees (0.5-2%), valuation charges (₹200-500), documentation fees (₹100-300), and ongoing vault/insurance charges all come out before you see the money.
- Real-world gap: a ₹2,00,000 loan advertised at 12% p.a. can carry an effective APR closer to 15%+ once every fee is added in.
- Auction risk: missed bullet-repayment deadlines can trigger swift auction notices — the same speed that got you the loan works against you on default.
0.99%/mo
Advertised Teaser Rate
24-36%
Real Rate After Default
22K→18K
Typical Purity Haircut
15.17%
Effective APR on a ₹2L Loan
The True Cost — Advertised vs Real, ₹2,00,000 Loan Over 12 Months
| Fee Component | Advertised Promise | Actual Cost |
|---|---|---|
| Sanctioned amount | ₹2,00,000 | ₹2,00,000 |
| Nominal interest (12% p.a.) | ₹24,000 | ₹24,000 |
| Processing fee (1.5% + GST) | Claimed zero/waived | ₹3,540 |
| Valuation & admin fees | Not mentioned | ₹1,000 |
| Vault storage & insurance | Not mentioned | ₹1,800 |
| Total cost of loan | ₹2,24,000 | ₹2,30,340 |
| Effective APR | 12.00% | 15.17% |
Why 15-Minute Gold Loan 2026 Ads Work — The Emotional Playbook
Financial distress narrows how carefully people read contracts. Lenders lean on three triggers deliberately:
- The urgency hook: “15-minute disbursal” pushes you past the instinct to ask for a Key Fact Statement (KFS) or read the terms.
- The zero-friction illusion: “No CIBIL required,” “zero income proof” — framed as a favour, not a high-interest secured loan.
- Normalising the pledge: ads present pledging family gold as a smart, temporary fix, downplaying that losing it in an auction is a real possibility on default.
Regulated NBFCs vs Illegal Lending Apps
| Factor | Regulated NBFCs / Banks | Unregistered / Illegal Apps |
|---|---|---|
| Examples | Muthoot, Manappuram, IIFL, major banks | Fake fintech apps with no physical branch |
| Legal status | RBI-compliant, licensed | Unregulated, often untraceable |
| Cost structure | High but disclosed in the KFS | Hidden fees, upfront UPI payments demanded |
| Recovery practice | Legal auction process after due notice | Data harassment, extortion tactics reported |
| Your risk | Expensive loan if you don’t read the fine print | Losing money with no loan disbursed at all |
The single clearest red flag across both categories: anyone asking for an upfront processing fee via UPI before disbursing the loan is running a scam, not offering a 15-Minute Gold Loan 2026 product. Legitimate lenders deduct fees from the disbursed amount — they never ask you to pay in first.
Checklist Before You Pledge Your Gold
- Demand the Key Fact Statement (KFS): the one-page document listing total APR, processing fees, penalty slabs, and foreclosure charges. Don’t sign without it.
- Check the purity and weight receipt: it should explicitly show Gross Weight, Net Weight (excluding stones), and assessed purity, e.g. 22K.
- Never pay upfront fees: genuine NBFCs deduct charges from the disbursal, not before it.
- Understand your repayment schedule: for bullet-repayment loans (interest and principal together at maturity), know the exact deadline to avoid an auction flag.
- Compare the effective APR, not the teaser rate: use a loan cost calculator or the BadaBanker Calculator app to add in every fee before you agree to anything.
📋 Our Verdict — 15-Minute Gold Loan 2026
“A 15-Minute Gold Loan 2026 from a registered NBFC or bank is a legal, fast source of emergency liquidity — not a scam. But speed is exactly what these lenders use to stop you from reading the fine print. Ask for the KFS, check the purity receipt, refuse to pay anything upfront, and calculate your real APR before you hand over family gold. The gold is replaceable in theory. In practice, for most families, it isn’t.”
15-Minute Gold Loan 2026 — FAQs
Q: Is a 15-minute gold loan actually a scam?
A: Not if it’s from a registered NBFC or bank — it’s a legal, RBI-regulated product. It becomes a scam only when an unregistered app asks for upfront fees via UPI without ever disbursing a loan.
Q: Why do gold loan NBFCs undervalue my jewellery?
A: Rapid 15-minute assays deduct for solder, stones, and craftsmanship aggressively to save time, often valuing 22-karat gold closer to 18-karat equivalents — which lowers your eligible loan amount.
Q: What happens if I miss a payment on a gold loan?
A: Many teaser-rate loans convert to a much higher interest slab, sometimes 24-36% APR with compounding penalties, and continued default can lead to your gold being auctioned after due notice.
Q: How do I calculate the real cost of a gold loan before signing?
A: Add the nominal interest to every disclosed fee — processing, valuation, documentation, storage and insurance — over your loan tenure, then compare that total to the sanctioned amount to get your true effective APR. The Key Fact Statement should have all these figures listed.
Run your own numbers with the Loan Cost Calculator or the BadaBanker Calculator app, or browse more Loans coverage on BadaBanker.
📎 Sources: RBI — Gold Loan Regulatory Guidelines. For informational purposes only. Gold loan rates, valuation methods, and fees vary by lender — always request the Key Fact Statement before signing.