RBI gold loan new rules 2026 — which lenders had to adopt by April 1, 2026 — completely changed how every Indian borrower can pledge gold. From tiered LTV ratios to mandatory 7-day gold return with ₹5,000/day penalty, these changes protect you in ways the old rules never did. Here is everything you need to know.

Lenders had to follow the new rules by April 1, 2026. More money on same gold. Faster return. Transparent auction. Know your new rights.
📅 Last Updated: May 3, 2026 | ⏱️ Reading Time: 12 minutes | Source: RBI Circular RBI/2025-26/47
The new rules are live and mandatory for ALL regulated entities — banks and NBFCs. Existing loans must be aligned by July 2026. Key changes include tiered LTV, 12-month bullet repayment cap, mandatory 7-day gold return with ₹5,000/day penalty, and formal silver loan regulation. Non-compliance attracts RBI penalisation.
📋 Quick Summary: RBI completely revamped its gold loan rules , with lenders required to comply by April 1, 2026. Key changes: Tiered LTV — 85% for loans up to ₹2.5L (was flat 75%), 7-day mandatory gold return with ₹5,000/day penalty, transparent auction process, silver loans formally regulated, and bullet repayment capped at 12 months. Small borrowers benefit most — up to ₹20,000 more cash on same gold.
Here is an example of how the new rules play out for one family. There was an aunty with old gold bangles in her hands and hope in her eyes. Her daughter’s college fees were due — she needed ₹2 lakh urgently.
She first went to one lender, who offered 75% LTV at the counter. A second lender offered 85% on the same gold — a ₹20,000 difference. The aunty was confused. “My brother got 75% six months ago. How is it 85% now?”
That’s exactly what changed under the new rules. The RBI rewrote its gold loan rules in June 2025, and lenders had to comply by April 1, 2026. Today we explain exactly that — from the banking industry’s point of view, with real numbers.
Free tool
Estimate the monthly repayment on a loan with the Loan EMI calculator.
Estimates only. Check current terms with your bank before you decide.
Before vs After: What Changed
Before April 1, 2026
- Flat 75% LTV on all gold loans
- ₹1 lakh gold → only ₹75,000 loan
- Bullet repayment — unlimited renewals
- Gold return — 15-20 days (no penalty)
- Auction process — opaque, no borrower rights
- Surplus after auction — lender kept it
- Silver loans — informal, unregulated
- Valuation — subjective, lender decides
After April 1, 2026 (New RBI Rules)
- Tiered LTV — 85%/80%/75% based on amount
- ₹1 lakh gold → ₹85,000 loan (small loans)
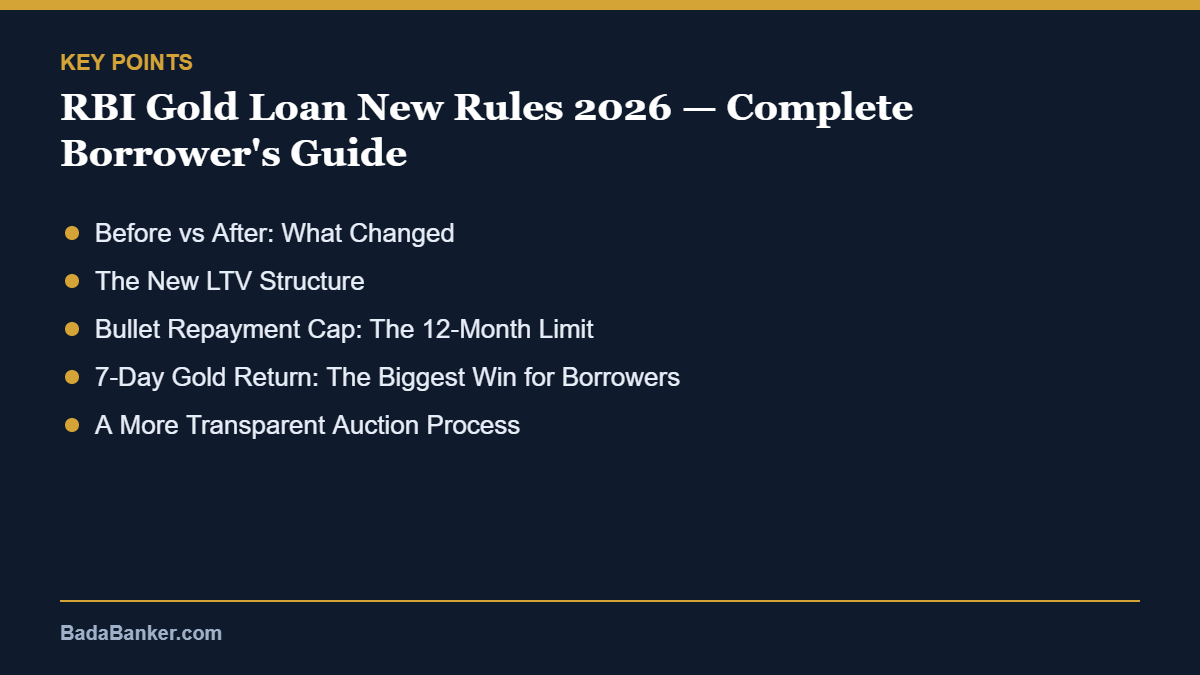
- Bullet repayment — max 12 months
- Gold return — 7 working days (₹5K/day penalty)
- Auction — transparent, advance notice, reserve price
- Surplus — mandatory return to borrower in 7 days
- Silver loans — formally regulated by RBI
- Valuation — standardized (IBJA rates, 30-day avg)
The New LTV Structure
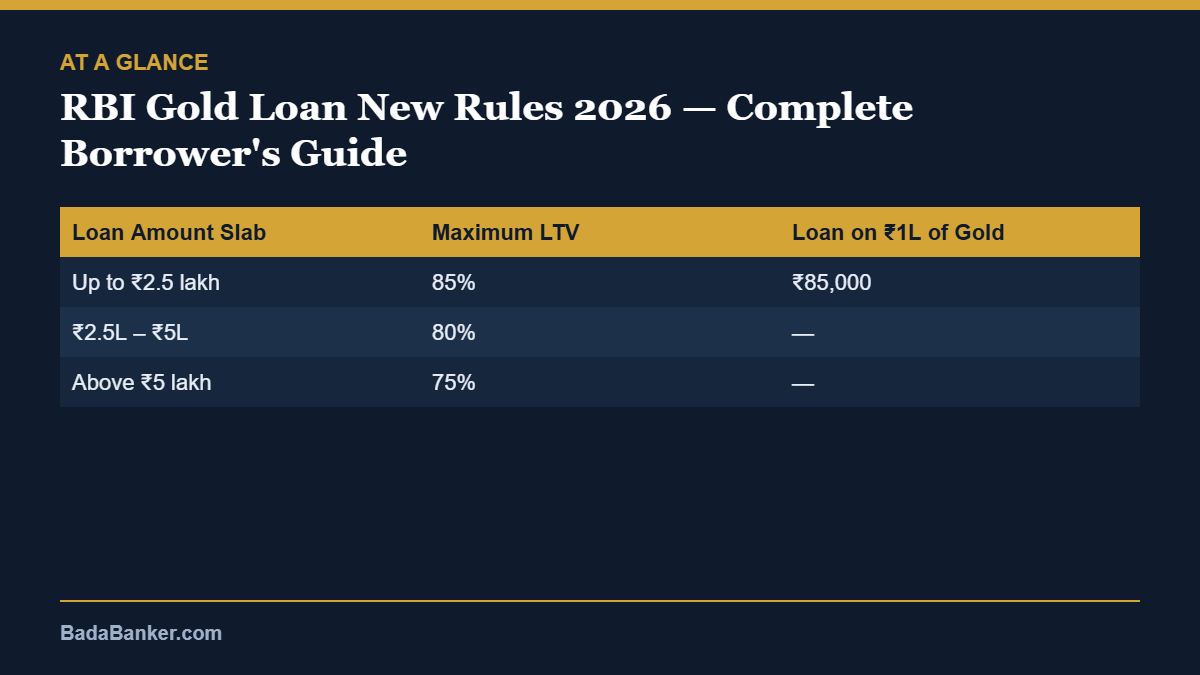
The most important change in the new rules — LTV (Loan-to-Value) is now tier-based instead of flat 75%:
| Loan Amount Slab | Maximum LTV | Loan on ₹1L of Gold | Example — ₹3L Gold |
|---|---|---|---|
| Up to ₹2.5 lakh | 85% | ₹85,000 | ₹2,12,500 (within slab) |
| ₹2.5L – ₹5L | 80% | — | ₹2,40,000 |
| Above ₹5 lakh | 75% | — | — |
In the aunty’s case, ₹2 lakh worth of gold used to fetch ₹1.5 lakh (75%). Now the same gold fetches ₹1.7 lakh (85%). That is ₹20,000 more cash in a single transaction — on the same gold. Her daughter’s fee was paid, and a ₹20,000 emergency reserve stayed in her hands.
Illustrative Borrower Scenarios
Scenario 1 — Small Borrower (Wins Big)
Ramesh ji, an autorickshaw owner in Pune. His mother’s 80 gm chain is worth ₹6.5 lakh. He needs ₹2 lakh for his daughter’s wedding. Before: He had to pledge 35 gm of gold. Now (under the new rules): He only needs to pledge a 30 gm chain for the same ₹2L. Less gold pledged, more security retained at home.
Scenario 2 — Mid Borrower
Sunita ji, a school teacher in Lucknow. She needs a ₹4.5L loan (medical emergency). She has 100 gm of gold (₹8 lakh value). Before: 75gm gold pledge. Ab: Only 70 gm of gold pledged. She can keep 5 gm of gold at home = a ₹40,000 emergency reserve. Small but significant change under the new rules.
Scenario 3 — Large Borrower (No Change)
Vikram ji, a businessman in Surat. ₹15L working capital against gold. Above the ₹5L slab, still 75% LTV. No change for large borrowers — the government’s focus was on small borrowers. By design. The new rules specifically target the common person.
The RBI specifically targeted the common person in the 2026 gold loan circular. Big borrowers (above ₹5L) stayed at 75%. Small borrowers up to ₹2.5L — who account for 80% of gold loan volume — got 10% extra leverage. This is conscious policy design. Not accidental.
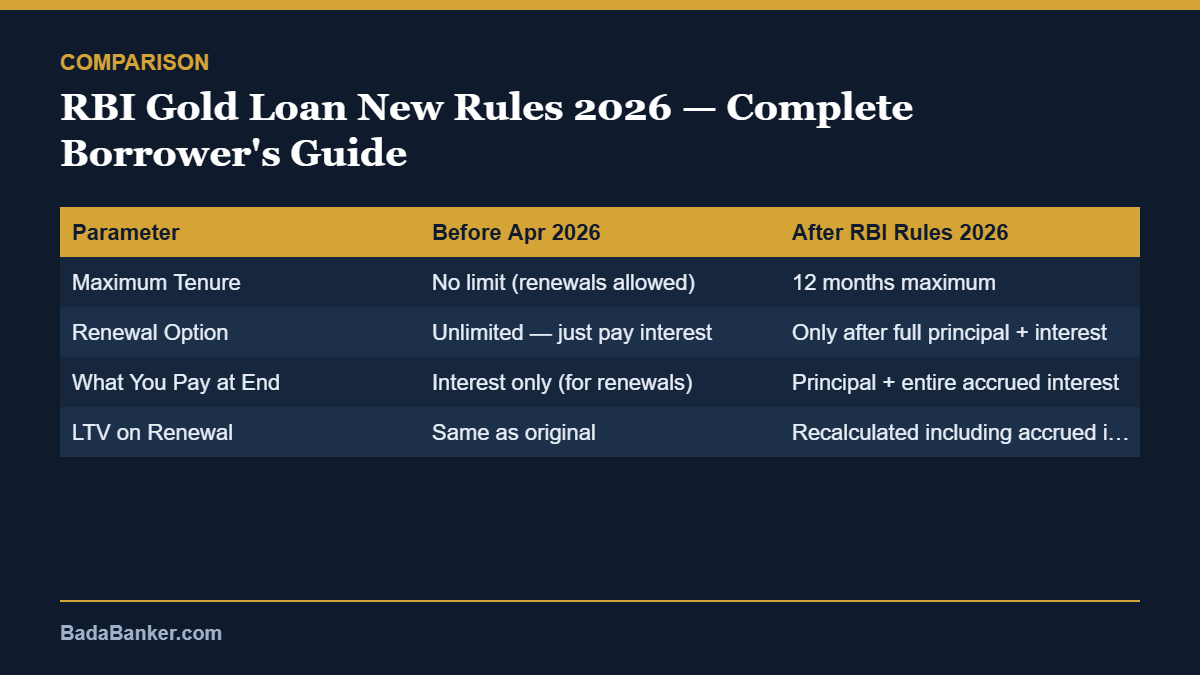
Bullet Repayment Cap: The 12-Month Limit
If you miss this change, it can become a big problem under the new RBI framework.
| Parameter | Before Apr 2026 | After RBI Rules 2026 |
|---|---|---|
| Maximum Tenure | No limit (renewals allowed) | 12 months maximum |
| Renewal Option | Unlimited — just pay interest | Only after full principal + interest |
| What You Pay at End | Interest only (for renewals) | Principal + entire accrued interest |
| LTV on Renewal | Same as original | Recalculated including accrued interest |
Bullet repayment loans make up 65% of gold loans in India today. The new 12-month limit under the new rules means that if you do not pay principal + interest within 12 months, it becomes a formal default. A CIBIL score impact is possible. The EMI option is now safer. Uncertain cash flow? Choose EMI, not bullet.
Real Example: ₹2 lakh bullet loan, 12% interest, 1 year. At the end you must pay: ₹2L principal + ₹24,000 interest = ₹2,24,000. Want a renewal? First clear the ₹24,000 — only then will you get a new loan under the new rules.
7-Day Gold Return: The Biggest Win for Borrowers
A common complaint used to be: “I repaid the loan, but it is taking 15–20 days to get my gold back.” Now the new rules change this rule completely:
| Element | New Rule (April 2026) |
|---|---|
| Gold Return Deadline | 7 working days from loan closure |
| Late Return Penalty | ₹5,000 per day — lender pays YOU |
| Excuses Accepted? | None — vault audit, branch transfer — all invalid |
| Where to Complain | RBI Banking Ombudsman — cms.rbi.org.in |
| Toll-free Number | 14448 |
Before you sign, tell the lender: “I want my gold back within 7 working days of the loan closing. A ₹5,000/day penalty applies under the new rules.” Get a written commitment. In practice — make a written complaint and mention the RBI Ombudsman. Most lenders will release the gold immediately.
A More Transparent Auction Process
The most painful situation before: a borrower defaulted, the gold was auctioned, but no one could tell where the surplus went. The new rules fix this completely.
| Auction Element | Before | The new rules |
|---|---|---|
| Advance Notice | Often missing | Mandatory before auction |
| Reserve Price | Not declared | Must be declared to borrower |
| Lender Bidding | Allowed | Lender/related parties BANNED |
| Auction Surplus | Lender kept it | Mandatory return to borrower in 7 days |
| Documents Right | Not guaranteed | Borrower can demand all auction documents |
A ₹3 lakh gold loan defaulted. The auction fetched ₹4.5 lakh (gold prices had gone up). Before: the lender recovered ₹3.5L and kept the remaining ₹1L. Now under the new rules: the ₹1L must be returned to the borrower — within 7 days. That ₹1L could be the difference between recovery and ruin.
Silver Loans Now Recognised
Silver loans used to be informal. From April 2026, silver is formally regulated under the same new framework:
| Parameter | Silver Loan Details Under the New Rules |
|---|---|
| Eligible Collateral | Silver jewellery, ornaments, specific coins |
| LTV Structure | Same as gold — 85%/80%/75% tiered |
| Maximum per Borrower | 10 kg silver ornaments OR 500g silver coins |
| Pricing Reference | 30-day average IBJA/SEBI exchange rates |
| Same Protections? | Yes — 7-day return, auction rules, all apply |
🔵 Big Win for Rural India: Many rural households have silver, not gold (cultural preference). Before, these households were cut off from formal credit. Now even silver gets 85% LTV up to ₹2.5L — real financial inclusion under the new rules.
Standardised Gold Valuation
Before, every lender did its own valuation. The new rules made standardization mandatory:
| Valuation Element | New Standard (April 2026) |
|---|---|
| Price Reference | Lower of: 30-day average OR previous day’s price |
| Source | IBJA or SEBI exchange rates only |
| What Counts | Intrinsic gold value only — stones/gems = nil value |
| Purity Range | 18-22 karat mandatory |
| Method | XRF machine or hallmarking-based assaying |
| Borrower Presence | Mandatory during valuation — your right |
Heavy stone-studded jewellery is not ideal for a gold loan. A 50 gm necklace that is 50% stones will only count as 25 gm of gold value for you under the new rules. Plain gold pieces will fetch a larger loan. If you have a choice, pledge plain bangles/chains, not heavy stone sets.
Banks vs NBFCs After the New Rules
LTV, valuation and return rules are all the same now under the April 2026 RBI framework. The real differences:
| Parameter | Banks (SBI/HDFC/ICICI) | NBFCs (Muthoot/Manappuram) |
|---|---|---|
| Interest Rate | 9–12% p.a. | 10–18% p.a. (some up to 24%) |
| Disbursal Speed | 1–3 hours | 30 mins–1 hour |
| Documentation | More (strict KYC) | Less (especially small loans) |
| Branch Coverage | Better in urban areas | Stronger in tier 2/3 cities |
| LTV Rules | Same (new rules) | Same (new rules) |
| Auction Rules | Same (April 2026 RBI circular) | Same (April 2026 RBI circular) |
| Gold Return | Same 7 working days rule | Same 7 working days rule |
Loan up to ₹2L and urgent → NBFC (Muthoot/Manappuram) — faster processing. Higher amount, lower interest a priority → PSU bank (SBI/PNB/BoB). Already have an account with a bank → try that one first, KYC will be quick. Both are safe — the rules are the same now under the new rules.
5 Things to Do Before Taking a Gold Loan
Common Mistakes Borrowers Make
Mistake 1 — Borrowing at the maximum LTV
“I have ₹5 lakh of gold, I got 85% — I’ll take ₹4.25L.” But if the gold price falls next month, the lender will demand a top-up. Under the new rules, LTV is capped but price volatility risk is still yours. Always borrow 60–65% of value, not maximum LTV.
Mistake 2 — Multiple gold loans simultaneously
A loan from one bank, then another loan from an NBFC 3 months later. This will show on your CIBIL — and a CIBIL check is now mandatory above ₹2.5L under the new rules. Multiple secured loans in a short time damage your credit score.
Mistake 3 — Overconfidence in bullet repayment
“The business payment will come in 1 year, I’ll pay then.” The business payment came late — default. Gold lost. The 12-month deadline under the new rules is real now. Bullet only if you’re 200% sure of the repayment source.
Mistake 4 — Pledging a family member’s gold without proper permission
A common reason for joint family disputes. Before pledging, tell all stakeholders and get ownership clearly documented. Use your right under the new rules — borrower presence at valuation is now mandatory. Avoid family conflicts — they last longer than any loan.
Mistake 5 — Not reading the KFS document
Many people sign without reading. Hidden charges — locker fee, valuation fee, processing fee, foreclosure penalty. Under the new rules, KFS is mandatory — lender must give it. Always read it fully. Total cost can be ₹15,000–20,000 more than expected if you don’t read it.
Your Rights as a Borrower
- Gold return in 7 days: Your legal right under the new rules. Not a request — an RBI mandate.
- ₹5,000/day for late return: You can claim this. Written complaint + RBI Ombudsman.
- Auction surplus: If auction recovers more than loan amount — extra money is YOURS, mandatory within 7 days.
- Borrower presence at valuation: You have the right to be present. Don’t waive this under the new rules.
- Reserve price disclosure: Before auction, you must be told the minimum bid price.
- KFS document: You have the right to receive this before signing. Demand it if not given.
- Complaint mechanism: RBI Banking Ombudsman at cms.rbi.org.in | Toll-free: 14448
Frequently Asked Questions
Do the new gold loan rules apply to existing loans?
No. The new rules apply to new loans sanctioned after April 1, 2026. Existing loans will continue on the old terms until renewal. At renewal, the new rules will apply automatically.
What does 85% LTV mean for a ₹2.5 lakh gold loan?
If your total gold loan is ₹2.5 lakh or less, you get a maximum of 85% LTV under the new rules. That means ₹85,000 against ₹1 lakh worth of gold. If you need ₹3 lakh, you get 85% on the first ₹2.5L and 80% on the remaining ₹50K (next tier).
Have bullet repayment gold loans been stopped under the new RBI rules?
No — they are still available, but with a maximum tenure of 12 months under the new rules. At the end, both principal and accrued interest must be cleared. Earlier, unlimited renewals were possible; now they are not.
Is a CIBIL score checked for a gold loan under the new rules?
Loans up to ₹2.5 lakh — minimal CIBIL check. Above ₹2.5 lakh — mandatory CIBIL + credit assessment under the new rules. Score below 600 may face higher interest rates even for gold loans now.
Do you really get ₹5,000 a day for a late gold return under the new RBI rules?
Yes — it is a mandate of the new rules. After 7 working days, the bank/NBFC must pay ₹5,000 for every day of delay. Make a written complaint, and say you will file it with the RBI Banking Ombudsman — most lenders will release the gold immediately.
Can you get a silver loan just like a gold loan?
Yes — from April 2026, silver is formally regulated under the same RBI framework. Silver jewellery, ornaments and specific coins are eligible. Same LTV structure (85%/80%/75%). Maximum 10 kg of ornaments / 500 g of coins per borrower.
Do you get back the surplus from a gold loan auction under the new rules?
Yes — absolutely. Under the new rules, if the gold sells for more at auction (more than loan + interest + charges), the surplus must be returned to the borrower within 7 working days. The lender cannot keep it.
Bank or NBFC: which is better now?
LTV, valuation, return and auction rules are all the same now under the April 2026 rules. Real difference: Banks offer 9–12% interest (cheaper), NBFCs disburse faster (30 min vs 1–3 hours). Small urgent loan → NBFC. Large planned loan → bank.
Do you have to give an end-use declaration for a gold loan?
Yes — for loans above ₹2 lakh, a declared end-use purpose is now mandatory under the new rules. Medical, agriculture, education, business working capital — all are accepted categories. “Investment in stock market” is explicitly NOT allowed as an end-use for gold loans.
Banker’s Verdict
The RBI’s framework is genuinely borrower-friendly. Changes in the banking sector are often lender-favorable — but this is a real consumer protection law. The new rules have given priority to the common person — not just on paper, but in real implementation.
The benefit to small borrowers is real — 10% extra leverage, 7-day gold return with a ₹5,000 daily penalty, transparent auctions, formal silver loans. But stay disciplined — the 12-month limit on bullet repayment is serious. Larger loans will get a CIBIL check. Stone-heavy jewellery will be valued lower.
The example I started with — the daughter’s college fees. Under the new rules, the same gold brought ₹20,000 more cash. Her fee was paid, and a ₹20,000 emergency reserve stayed in her hands. That’s what good banking regulation looks like.
Also Read on BadaBanker
Sources & References
- Reserve Bank of India — Gold Loan Circular April 2026 — rbi.org.in
- RBI Master Directions on Gold Loans — updated April 1, 2026 — rbi.org.in
- India Bullion and Jewellers Association (IBJA) — Gold pricing standards — ibja.co
- RBI Banking Ombudsman Scheme — cms.rbi.org.in | Toll-free: 14448
- Muthoot Finance — Gold Loan Product Terms — muthootfinance.com
- SBI Gold Loan — Official product page — sbi.co.in
- HDFC Bank Gold Loan Terms 2026 — hdfcbank.com