Senior citizen FD rates at India’s large banks top out between 7.05% and 7.35% a year in October 2026, while some small finance banks pay 7.90% or more and the Senior Citizens Savings Scheme pays 8.2%. This guide compares the senior citizen FD rates published by SBI, PNB, Bank of Baroda, Canara Bank, HDFC Bank, ICICI Bank, Axis Bank, Kotak Mahindra Bank, IDFC FIRST Bank and two small finance banks, explains the RBI’s new deposit-rate rules from 1 October 2026, and shows how to cut the tax on your interest.
Last checked: 18 October 2026, from each bank’s own website. Rates are for deposits below ₹3 crore. Senior citizen FD rates change often, so confirm the rate on the day you book.
Senior citizen FD rates in October 2026: the key points
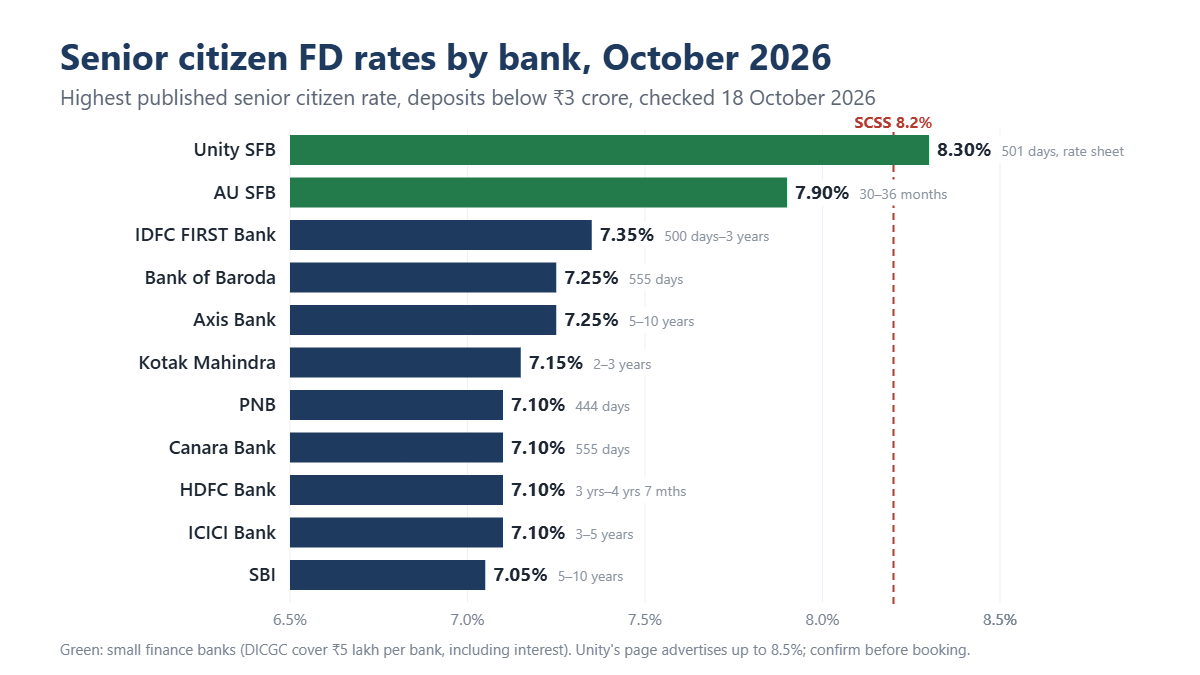
- Best large-bank rates: IDFC FIRST Bank 7.35% (500 days to 3 years), Bank of Baroda 7.25% (555 days) and Axis Bank 7.25% (5 to 10 years).
- Small finance banks pay more: AU Small Finance Bank pays up to 7.90% and Unity Small Finance Bank up to 8.30% on its 501-day deposit, according to their published rate sheets.
- The repo hike hasn’t reached most FD rates yet: the RBI raised the repo rate to 5.50% on 7 October 2026, but of the banks below, only ICICI Bank has published a new rate card since (effective 17 October).
- SCSS still leads: the Senior Citizens Savings Scheme pays 8.2% for October to December 2026, up to ₹30 lakh per person.
- New RBI rules from 1 October: banks must pay exactly the rates shown on their website, the same at every branch.
- Tax: banks deduct TDS only when a senior’s interest from that bank crosses ₹1 lakh a year. From April 2026, Form 121 replaces Form 15H.
Free tool
Estimate what a deposit will be worth at maturity with the fixed deposit maturity calculator, or compare bank offers with the deposit rate comparison.
Estimates only. Check current terms with your bank before you decide.
Senior citizen FD rates at public sector banks
Government-owned banks pay senior citizens 0.50 percentage points over the regular rate on most tenures, and more on some longer deposits. Their best rates are usually on special tenures such as 444 or 555 days.
| Bank | 1 year | Highest senior rate (tenure) | Super senior (80+) | Rates effective |
|---|---|---|---|---|
| Bank of Baroda | 6.75% | 7.25% (555 days, bob Golden Goal) | 7.35% (555 days) | 12 June 2026 |
| PNB | 6.75% | 7.10% (444 days) | 7.40% (444 days) | 1 June 2026 |
| Canara Bank | 6.75% | 7.10% (555 days) | Extra on 444 and 555 days | 17 March 2026 |
| SBI | 6.75% | 7.05% (5 to 10 years, incl. SBI We-care) | +0.10 points (SBI Patrons) | 15 December 2025 |
SBI has not changed its senior citizen FD rates since 15 December 2025. Its best senior rate, 7.05% on 5-to-10-year deposits, includes the extra 0.50 points of the SBI We-care scheme. Bank of Baroda also pays seniors a full percentage point more than the public on 5-to-10-year deposits (7.00% against 6.00%), and PNB pays 0.80 points more (6.80% against 6.00%).
Senior citizen FD rates at private banks
| Bank | 1 year | Highest senior rate (tenure) | Senior extra | Rates effective |
|---|---|---|---|---|
| IDFC FIRST Bank | 6.75% | 7.35% (500 days to 3 years) | 0.25 points | 1 September 2026 |
| Axis Bank | 6.75% | 7.25% (5 to 10 years) | 0.50 points (0.75 on 5 to 10 years) | 1 July 2026 |
| Kotak Mahindra Bank | 6.85% | 7.15% (2 to under 3 years) | 0.50 points | 23 September 2026 |
| HDFC Bank | 6.75% | 7.10% (3 years 1 day to under 4 years 7 months) | 0.50 points (0.60 on that tenure) | 19 August 2026 |
| ICICI Bank | 6.75% | 7.10% (3 years 1 day to 5 years) | 0.50 points (0.60 on that tenure) | 17 October 2026 |
IDFC FIRST Bank has the highest senior citizen FD rates among large private banks even though it adds only 0.25 points for seniors, because its regular rate (7.10% for 500 days to 3 years) is already high. Axis Bank is the best of this group for a 5-to-10-year deposit at 7.25%.
Senior citizen FD rates at small finance banks
- AU Small Finance Bank: 7.90% for seniors on 30 months 1 day to 36 months, and 7.60% on 12 to 15 months. AU says senior rates apply to resident senior citizens who have a banking relationship with it.
- Unity Small Finance Bank: 8.30% for seniors on its 501-day deposit and 8.00% on 12 months, according to the rate sheet linked from its fixed deposit page (rates revised from 11 June 2026). The page itself advertises “up to 8.5%”, so confirm the current 501-day rate before you book.
Small finance banks are regulated by the RBI and covered by DICGC deposit insurance, just like large banks. The difference is the cushion behind that insurance. DICGC insures up to ₹5 lakh per depositor per bank, and that limit includes interest. So keep principal plus expected interest at one small finance bank within ₹5 lakh. A deposit of ₹4.5 lakh, for example, leaves room for interest. For more banks and tenures, see our small finance bank FD rates guide.
Post office and government schemes for senior citizens
The government kept small savings rates unchanged for 1 October to 31 December 2026. These schemes are backed by the government, so they carry no bank risk.
| Scheme | Rate (Oct–Dec 2026) | Limit | Tenure and payout |
|---|---|---|---|
| Senior Citizens Savings Scheme (SCSS) | 8.2% | ₹30 lakh per person | 5 years, extendable by 3 years; interest paid quarterly |
| Post Office Monthly Income Scheme | 7.4% | ₹9 lakh single, ₹15 lakh joint | 5 years; interest paid monthly |
| Post Office Time Deposit, 5 years | 7.5% | No upper limit | 5 years |
| National Savings Certificate | 7.7% | No upper limit | 5 years; interest paid at maturity |
| RBI Floating Rate Savings Bonds | 8.05% (NSC rate + 0.35) | No upper limit | 7 years, with earlier exit for seniors; rate resets every 6 months |
Note that the Pradhan Mantri Vaya Vandana Yojana (PMVVY), which older articles still recommend, closed to new investors in March 2023.
What ₹10 lakh earns in a year
Here is how senior citizen FD rates compare with government schemes. The table shows the yearly interest on ₹10 lakh if you take the interest out as it is paid instead of reinvesting it, before tax. The gap between a 1-year bank FD and SCSS is ₹14,500 a year.
| Option | Senior rate | Interest a year on ₹10 lakh |
|---|---|---|
| 1-year FD at SBI, PNB, HDFC, ICICI or Axis | 6.75% | ₹67,500 |
| HDFC or ICICI, about 3 to 5 years | 7.10% | ₹71,000 |
| IDFC FIRST Bank, 500 days to 3 years | 7.35% | ₹73,500 |
| Post Office Monthly Income Scheme | 7.4% | ₹74,000 |
| AU Small Finance Bank, 30 to 36 months | 7.90% | ₹79,000 |
| SCSS | 8.2% | ₹82,000 |
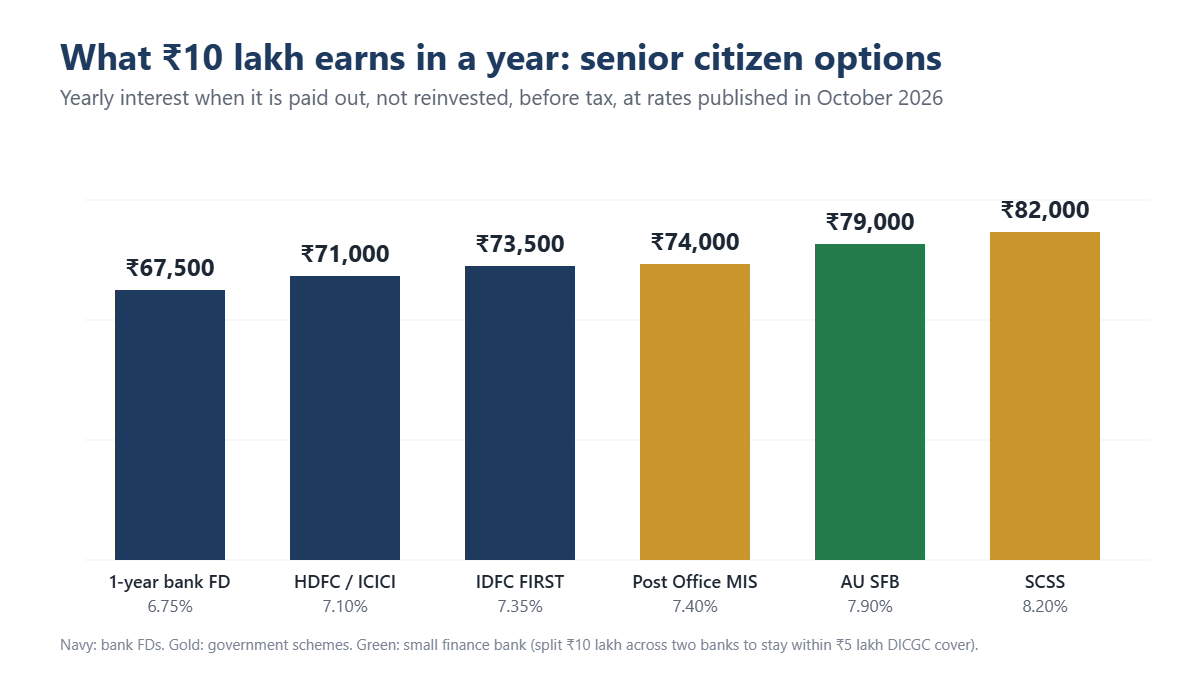
A ₹10 lakh deposit at one small finance bank would exceed the ₹5 lakh insurance limit, so for that option, split the amount between two banks.
New RBI rules on deposit rates from 1 October 2026
The RBI’s Interest Rate on Deposits Second Amendment Directions, 2026, issued on 30 July 2026, took effect on 1 October 2026. They don’t set FD rates, but they change how banks apply them:
- Rates as per the website: interest on all deposits must be paid strictly as per the rate schedule the bank discloses in advance on its website.
- Same rate at every branch: rates must be uniform across branches and customers, with no difference between deposits of similar amount accepted on the same date.
- Bulk deposits: rates for bulk deposits must be posted on the website by 10:10 am every business day.
For senior citizens, this means the senior citizen FD rates published on a bank’s website are the rates you should get. Before booking, check the bank’s website for that day’s rate and compare it with what the branch offers. Similar directions apply to small finance banks, regional rural banks and urban co-operative banks.
Tax on senior citizen FD interest in 2026
The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026. The main rules for senior depositors:
- TDS threshold: a bank deducts TDS only when a senior citizen’s interest from that bank in the financial year exceeds ₹1 lakh. Give the bank your PAN, or TDS will be deducted at a higher rate.
- Form 121 replaces Form 15H: if the tax on your estimated total income for the year will be nil, submit Form 121 to each bank at the start of the year so it doesn’t deduct TDS.
- ₹50,000 deduction: under Section 153 of the new Act (earlier Section 80TTB), senior citizens can deduct up to ₹50,000 of interest from bank, co-operative bank and post office deposits. This applies only if you choose the old tax regime.
- New tax regime: resident individuals with total income up to ₹12 lakh pay no income tax because of the rebate. Many retirees whose income is mainly pension and interest fall within this.
Interest is taxable whether or not TDS is deducted, so include it in your return. Our guide to TDS on FD interest explains Form 121 in more detail.
How to choose the right FD as a senior citizen
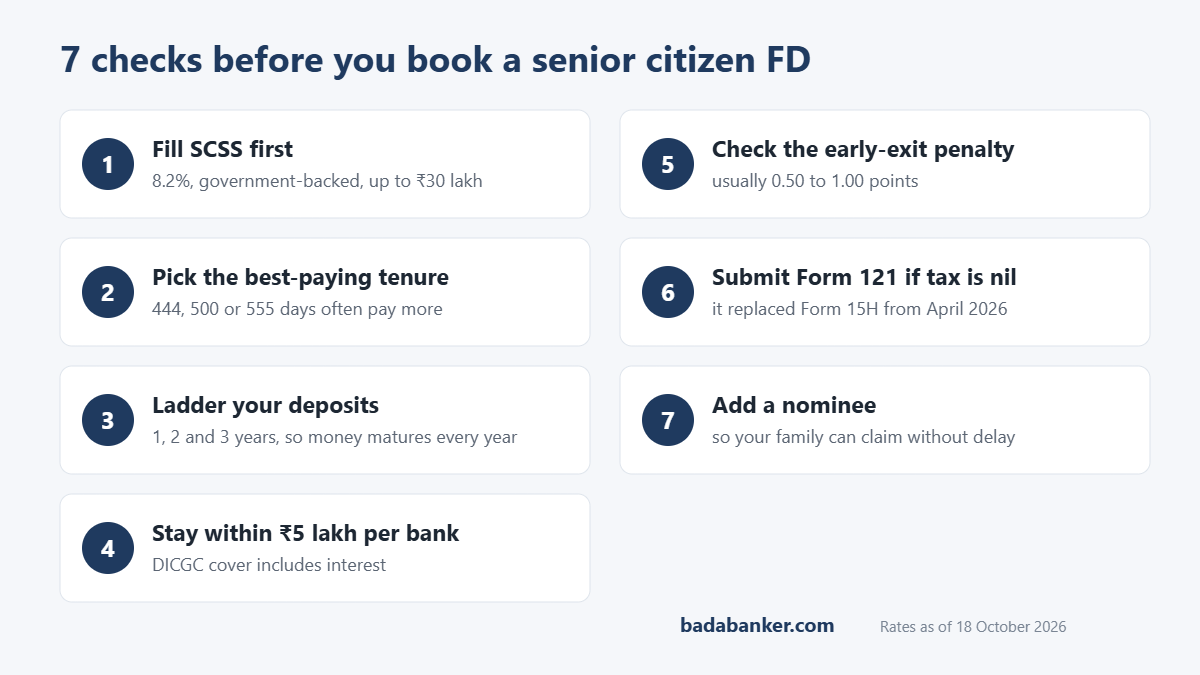
- Fill SCSS first if you need regular income and have not used the ₹30 lakh limit. Its 8.2% is fixed for the full 5 years at the rate on the day you invest.
- Match the tenure to the best rate. Many banks pay their top rate on one special tenure, such as 444, 500 or 555 days. A few days either way can cost you 0.25 to 0.50 points.
- Ladder your deposits. Split money across 1, 2 and 3-year FDs so part of it matures every year. If banks raise FD rates after the October repo hike, you can reinvest at the new rates.
- Stay within the ₹5 lakh insurance limit at small finance banks, counting interest.
- Check premature withdrawal penalties. Most banks cut 0.50 to 1.00 points if you break an FD early. Non-callable deposits can’t be broken at all.
- Choose monthly or quarterly payout if you need income. A cumulative FD earns slightly more, but pays only at maturity.
- Add a nominee to every deposit so your family can claim it without delay.
Frequently asked questions
Which bank has the best senior citizen FD rates in October 2026?
Among large banks, IDFC FIRST Bank pays 7.35% for 500 days to 3 years, followed by Bank of Baroda (7.25% for 555 days) and Axis Bank (7.25% for 5 to 10 years). Small finance banks pay more, such as AU at 7.90% and Unity at 8.30% on its published rate sheet.
Will senior citizen FD rates go up after the repo hike?
Banks decide their own deposit rates. A repo rate hike raises their cost of funds and often leads to higher FD rates over the following weeks, but not automatically. As of 18 October 2026, ICICI Bank is the only bank in our list with a rate card dated after the 7 October hike. We will update these senior citizen FD rates as banks revise their rate cards.
How much extra interest do senior citizens get?
Usually 0.50 percentage points over the regular rate. IDFC FIRST Bank gives 0.25 points. Some banks give more on longer deposits: SBI and Bank of Baroda 1.00 point on 5 to 10 years, PNB 0.80 and Axis 0.75. SBI, PNB and Bank of Baroda also pay super senior citizens (80 and above) a little more.
Is SCSS better than a bank FD?
For most seniors, yes, up to its ₹30 lakh limit. It pays 8.2%, which is higher than any large bank’s FD rate, and it is backed by the government. The trade-offs are the 5-year tenure and a penalty if you close it early.
Are small finance bank FDs safe for senior citizens?
They are RBI-regulated banks, and deposits are insured by DICGC up to ₹5 lakh per depositor per bank, including interest. Keep each small finance bank deposit within that limit, and spread larger amounts across banks.
How can a senior citizen avoid TDS on FD interest?
No TDS is deducted if your interest from a bank stays within ₹1 lakh a year. Above that, submit Form 121 to the bank at the start of the financial year if the tax on your total income will be nil.
Related reading
Sources
- SBI, Retail domestic term deposits (effective 15 December 2025)
- PNB, Interest rates on deposits (effective 1 June 2026)
- Bank of Baroda, Fixed deposits up to ₹10 crore (effective 12 June 2026)
- Canara Bank, Term deposits rate of interest (effective 17 March 2026)
- HDFC Bank, FD interest rates (applicable from 19 August 2026)
- ICICI Bank, FD interest rates (effective 17 October 2026)
- Axis Bank, FD interest rates (domestic, below ₹3 crore, effective 1 July 2026)
- Kotak Mahindra Bank, Interest rates (effective 23 September 2026)
- IDFC FIRST Bank, FD interest rates (effective 1 September 2026)
- AU Small Finance Bank, Fixed deposit interest rates
- Unity Small Finance Bank, Fixed deposit page and linked rate sheet
- RBI, Interest Rate on Deposits Second Amendment Directions, 2026 (30 July 2026)
- DICGC, A guide to deposit insurance
- Income Tax Department, Form No. 121 and Section 153 of the Income-tax Act, 2025
- Ministry of Finance, office memorandum of 30 September 2026 on small savings rates for October to December 2026
Rates are as published by each bank on the date checked, for resident senior citizens and deposits below ₹3 crore. Banks can change rates without notice. This is general information, not personal investment advice.