15-Minute Gold Loan 2026 offers are everywhere right now — banners promising cash against your gold in 15 minutes, no income proof, no CIBIL check. When a medical emergency hits or a business payment is due tomorrow, that banner feels like a lifeline. It usually is a legal, RBI-regulated product. But the 15-Minute Gold Loan 2026 pitch is also frequently wrapped in marketing that hides the real cost behind the speed. Here’s what actually happens between the ad and the cash hitting your account.
I want to be clear upfront: a 15-Minute Gold Loan 2026 from a registered NBFC or bank is not a scam. It’s a legitimate, fast-moving product built on physical collateral — your gold — which is exactly why it can be disbursed so quickly. The problem isn’t legality. It’s what gets left out of the advertisement.
Quick Fact Check — 15-Minute Gold Loan 2026
- Teaser rates: advertised rates as low as 0.99% per month (~11.88% p.a.) are often introductory. If you miss a payment, a higher penal rate can apply, so check the penalty terms in the Key Fact Statement before you sign.
- Valuation: only the gold content counts. Stones, solder and making charges add nothing, so your loan is based on less than what you paid for the jewellery.
- Upfront deductions: processing fees (0.5-2%), valuation charges (₹200-500), documentation fees (₹100-300), and ongoing vault/insurance charges all come out before you see the money.
- Real-world gap: a ₹2,00,000 loan advertised at 12% p.a. can carry an effective APR closer to 15%+ once every fee is added in.
- Auction risk: missed bullet-repayment deadlines can trigger swift auction notices — the same speed that got you the loan works against you on default.
0.99%/mo
Advertised Teaser Rate
₹5,000/day
Compensation if gold return is delayed
90%
Minimum auction reserve price
15.17%
Effective APR on a ₹2L Loan
The True Cost of a 15-Minute Gold Loan — Advertised vs Real, ₹2,00,000 Over 12 Months
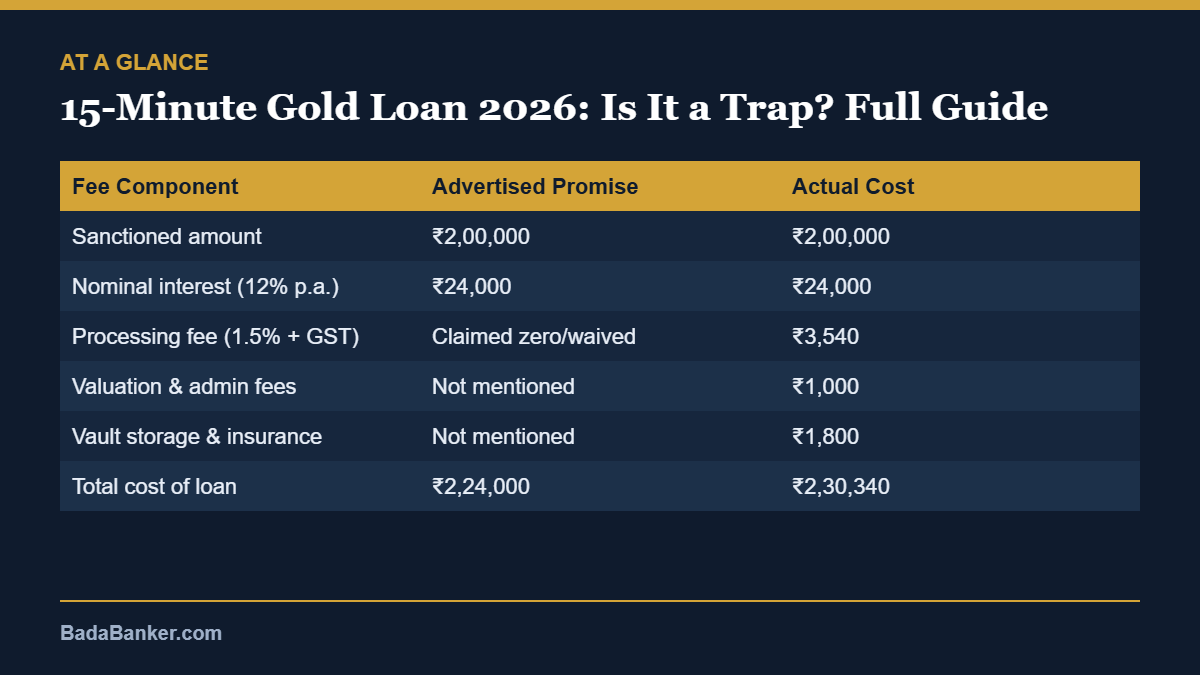
| Fee Component | Advertised Promise | Actual Cost |
|---|---|---|
| Sanctioned amount | ₹2,00,000 | ₹2,00,000 |
| Nominal interest (12% p.a.) | ₹24,000 | ₹24,000 |
| Processing fee (1.5% + GST) | Claimed zero/waived | ₹3,540 |
| Valuation & admin fees | Not mentioned | ₹1,000 |
| Vault storage & insurance | Not mentioned | ₹1,800 |
| Total cost of loan | ₹2,24,000 | ₹2,30,340 |
| Effective APR | 12.00% | 15.17% |
What the RBI Rules Require From Every Gold Lender
The RBI’s Lending Against Gold and Silver Collateral Directions, 2025 apply to banks and NBFCs alike, and lenders had to comply by April 1, 2026. Whatever the advertisement says, these protections apply to a gold loan from any regulated lender:
- How your gold is valued: at the lower of the average closing price over the previous 30 days and the previous day’s closing price for gold of that purity, as published by the IBJA or a SEBI-regulated commodity exchange. Only the gold content counts, not stones or making charges.
- Purity testing: the assaying process must be explained to you, and the details go into a certificate that you receive.
- Maximum loan: for consumption loans, up to 85% of the gold’s value if your total gold loans are up to ₹2.5 lakh, 80% above ₹2.5 lakh up to ₹5 lakh, and 75% above ₹5 lakh.
- Bullet loans: a loan where you repay principal and interest together at the end can run for at most 12 months, and the LTV limit applies to the total amount repayable at maturity.
- Getting your gold back: on the day you repay in full, and in any case within seven working days. If the lender causes a longer delay, it must pay you ₹5,000 for each extra day.
- Auction safeguards: an auction must be advertised in at least two newspapers, one in the regional language and one national; the reserve price must be at least 90% of the gold’s current value (85% if two auctions fail); and the lender and its related parties cannot bid. Any surplus must be returned to you within seven working days of the lender receiving the full proceeds.
Worked example: how much can a 15-minute gold loan give you?
Suppose your jewellery’s gold content is valued at ₹2,00,000 under the method above, and this is your only gold loan.
- EMI-style loan: the limit is 85% of ₹2,00,000, so you can borrow up to ₹1,70,000.
- 12-month bullet loan at 12% a year: the ₹1,70,000 limit applies to principal plus interest due at maturity. The most you can borrow is about ₹1,51,786, because ₹1,51,786 plus 12% interest comes to ₹1,70,000.
So the same gold supports a smaller bullet loan than an EMI loan. If a lender offers you more than these limits, ask how it is calculating the value, and get it in writing.
Why 15-Minute Gold Loan 2026 Ads Work — The Emotional Playbook
Financial distress narrows how carefully people read contracts. Lenders lean on three triggers deliberately:
- The urgency hook: “15-minute disbursal” pushes you past the instinct to ask for a Key Fact Statement (KFS) or read the terms.
- The zero-friction illusion: “No CIBIL required,” “zero income proof” — framed as a favour, not a high-interest secured loan.
- Normalising the pledge: ads present pledging family gold as a smart, temporary fix, downplaying that losing it in an auction is a real possibility on default.
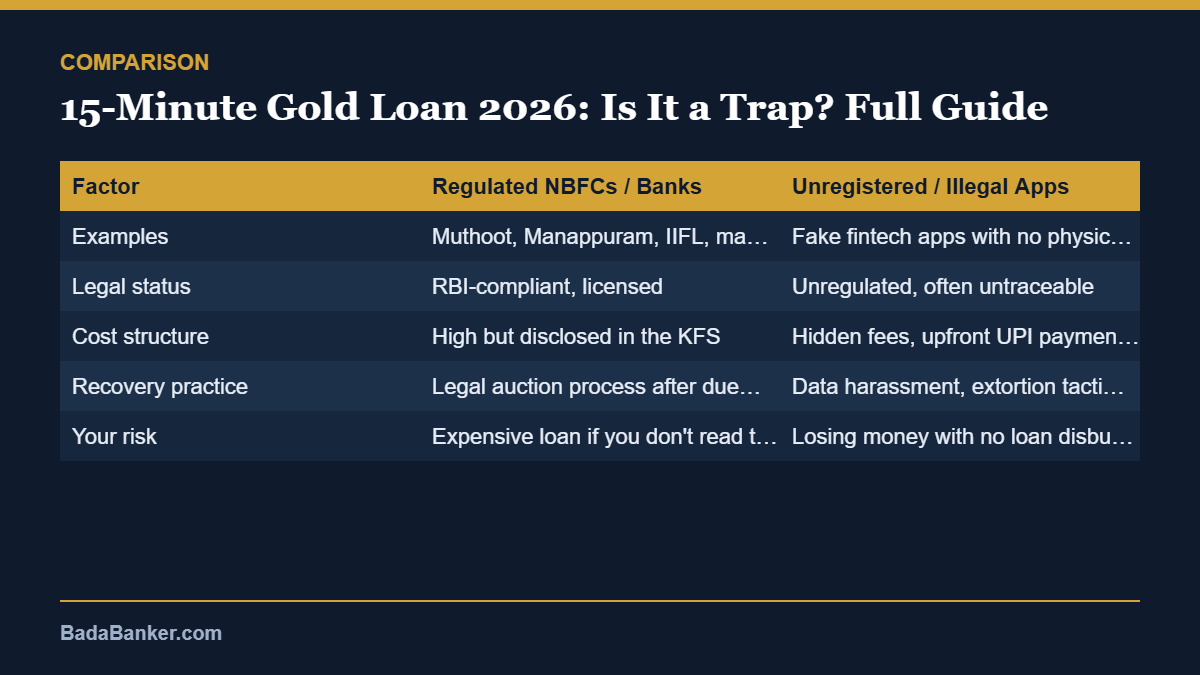
Regulated NBFCs vs Illegal Lending Apps
| Factor | Regulated NBFCs / Banks | Unregistered / Illegal Apps |
|---|---|---|
| Examples | Muthoot, Manappuram, IIFL, major banks | Fake fintech apps with no physical branch |
| Legal status | RBI-compliant, licensed | Unregulated, often untraceable |
| Cost structure | High but disclosed in the KFS | Hidden fees, upfront UPI payments demanded |
| Recovery practice | Legal auction process after due notice | Data harassment, extortion tactics reported |
| Your risk | Expensive loan if you don’t read the fine print | Losing money with no loan disbursed at all |
The single clearest red flag across both categories: anyone asking for an upfront processing fee via UPI before disbursing the loan is running a scam, not offering a 15-Minute Gold Loan 2026 product. Legitimate lenders deduct fees from the disbursed amount — they never ask you to pay in first.
15-Minute Gold Loan Checklist Before You Pledge Your Gold
- Demand the Key Fact Statement (KFS): the one-page document listing total APR, processing fees, penalty slabs, and foreclosure charges. Don’t sign without it.
- Check the purity and weight receipt: it should explicitly show Gross Weight, Net Weight (excluding stones), and assessed purity, e.g. 22K.
- Never pay upfront fees: genuine NBFCs deduct charges from the disbursal, not before it.
- Understand your repayment schedule: for bullet-repayment loans (interest and principal together at maturity), know the exact deadline to avoid an auction flag.
- Compare the effective APR, not the teaser rate: use a loan cost calculator or the BadaBanker Calculator app to add in every fee before you agree to anything.
📋 Our Verdict — 15-Minute Gold Loan 2026
“A 15-Minute Gold Loan 2026 from a registered NBFC or bank is a legal, fast source of emergency liquidity — not a scam. But speed is exactly what these lenders use to stop you from reading the fine print. Ask for the KFS, check the purity receipt, refuse to pay anything upfront, and calculate your real APR before you hand over family gold. The gold is replaceable in theory. In practice, for most families, it isn’t.”
15-Minute Gold Loan 2026 — FAQs
Q: Is a 15-minute gold loan actually a scam?
A: Not if it’s from a registered NBFC or bank — it’s a legal, RBI-regulated product. It becomes a scam only when an unregistered app asks for upfront fees via UPI without ever disbursing a loan.
Q: Why do gold loan NBFCs undervalue my jewellery?
A: Under the RBI rules, lenders value only the gold content of your jewellery, at its actual purity, using the lower of the 30-day average and the previous day’s published price. Stones, solder and making charges add nothing, so the value is usually well below what you paid. Check the purity and weight on the certificate the lender gives you.
Q: What happens if I miss a payment on a gold loan?
A: A penal rate or charges can apply, as set out in your Key Fact Statement. If the loan stays unpaid, the lender can auction your gold, but only after notice and following the RBI’s auction rules, and it must return any surplus to you.
Q: How do I calculate the real cost of a gold loan before signing?
A: Add the nominal interest to every disclosed fee — processing, valuation, documentation, storage and insurance — over your loan tenure, then compare that total to the sanctioned amount to get your true effective APR. The Key Fact Statement should have all these figures listed.
Run your own numbers with the Loan Cost Calculator or the BadaBanker Calculator app, or browse more Loans coverage on BadaBanker.
📎 Sources: RBI — Lending Against Gold and Silver Collateral Directions, 2025 (RBI/2025-26/47). For informational purposes only. Gold loan rates, valuation methods, and fees vary by lender — always request the Key Fact Statement before signing.
The advertised versus real cost table was eye-opening, especially how a loan shown at 12 percent actually works out to 15.17 percent once fees and storage are added. I also appreciated the warning that only gold content counts, not stones or making charges, since that changes what people expect to borrow. Your checklist to demand the Key Fact Statement before pledging anything is advice I will pass on to others.