If you’re a freelancer or business owner, advance tax isn’t optional. Paying the whole year’s tax in one lump sum in March costs you interest even if the total is correct, because the law expects the tax in four instalments through the year. This guide explains who must pay, the due dates, how the interest is calculated with worked examples, and what changed with the Income-tax Act, 2025, which renumbered the relevant sections from April 2026.
Quick Fact Check — Advance Tax 2026
- Who must pay: Anyone — salaried, freelancer, business owner, or investor — whose estimated tax liability for the year exceeds ₹10,000 after TDS/TCS credit.
- New for FY 2026-27: The Income Tax Act, 2025 has fully replaced the 1961 Act from April 1, 2026. Section 234B is now Section 424, Section 234C is now Section 425, and Section 234A is now Section 423. The rates and calculation method are unchanged — only the section numbers changed.
- Four installments: 15% by June 15, 45% (cumulative) by September 15, 75% (cumulative) by December 15, 100% by March 15.
- Interest rate: 1% per month on any shortfall, under both sections.
- Presumptive taxation relief: freelancers and small businesses using presumptive taxation (formerly Sections 44ADA and 44AD, now Section 58 of the 2025 Act) can pay their entire advance tax in one instalment by March 15, with no interest for the earlier quarters.
4 Installments
15% → 45% → 75% → 100%
1% / month
Interest rate on any shortfall
₹10,000
Threshold that triggers advance tax
Sec 424 & 425
New numbers for 234B & 234C

Why Freelancers Get Caught Out
Salaried employees rarely think about advance tax because their employer deducts TDS every month automatically. Freelancers and business owners don’t have that safety net — your clients may deduct some TDS, but it’s usually not enough to cover your full liability, especially once you factor in other income like interest or capital gains. The gap between what’s deducted and what you actually owe is exactly what advance tax is meant to cover, in real time, through the year.
The Real Cost of Waiting Until March
Here’s the mistake I see most often: a freelancer estimates their full-year tax correctly, but decides to just pay the whole thing in March instead of splitting it quarterly. This still attracts interest — because Section 425 (formerly 234C) penalizes you for missing each individual quarterly milestone, not just the year-end total.
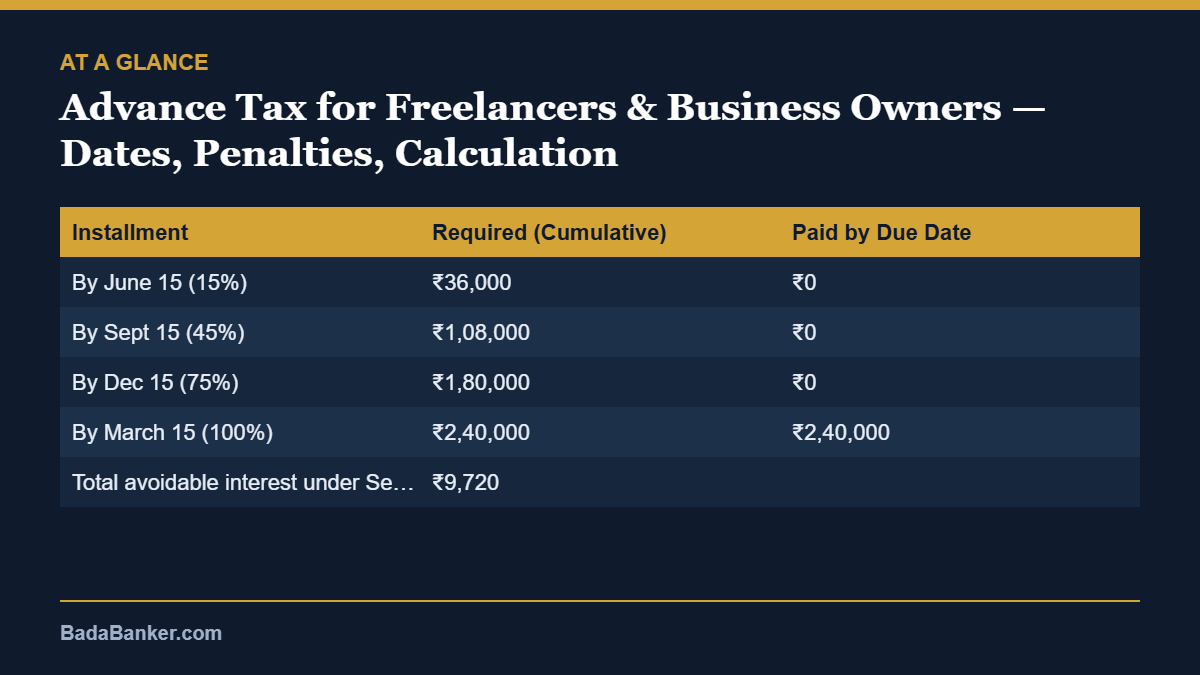
Take a freelancer with an estimated tax liability (after TDS credit) of ₹2,40,000 for the year, who pays nothing until paying the full amount on March 15.
| Installment | Required (Cumulative) | Paid by Due Date | Shortfall | Interest (1%/month) |
|---|---|---|---|---|
| By June 15 (15%) | ₹36,000 | ₹0 | ₹36,000 | ₹1,080 (3 months) |
| By Sept 15 (45%) | ₹1,08,000 | ₹0 | ₹1,08,000 | ₹3,240 (3 months) |
| By Dec 15 (75%) | ₹1,80,000 | ₹0 | ₹1,80,000 | ₹5,400 (3 months) |
| By March 15 (100%) | ₹2,40,000 | ₹2,40,000 | ₹0 | ₹0 |
| Total avoidable interest under Section 425 | ₹9,720 | |||
Tip: the ₹9,720 could have been avoided without paying any more tax, just by paying the same total in four parts on time.
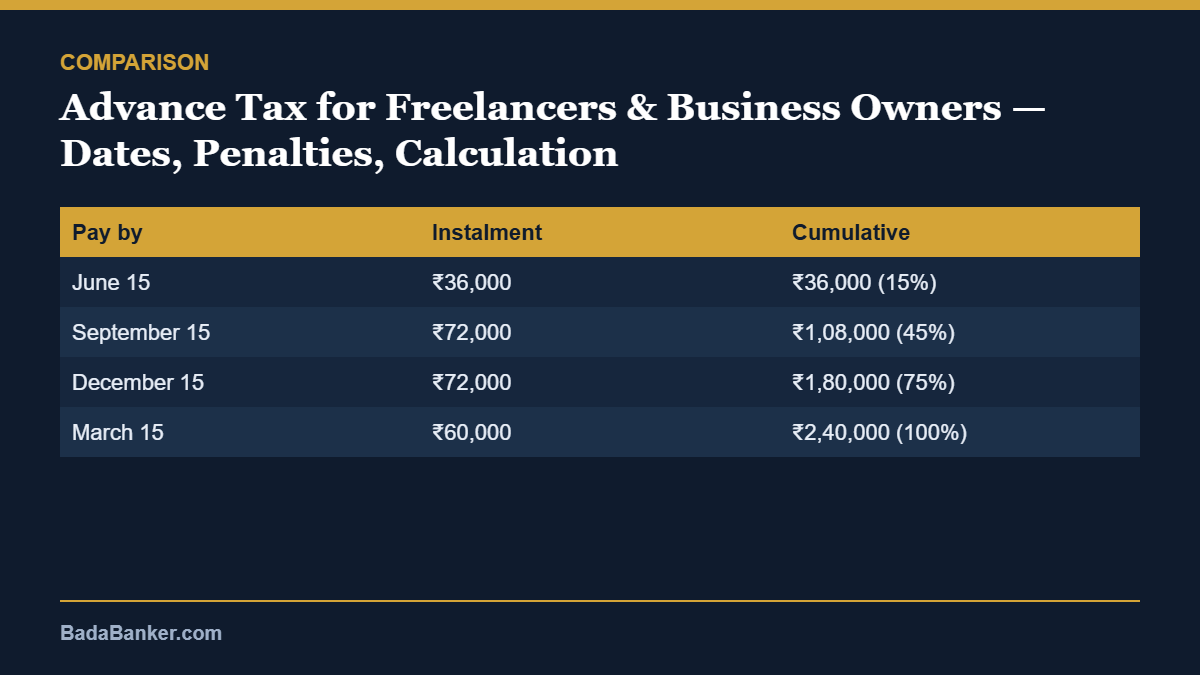
The on-time schedule for the same freelancer
| Pay by | Instalment | Cumulative |
|---|---|---|
| June 15 | ₹36,000 | ₹36,000 (15%) |
| September 15 | ₹72,000 | ₹1,08,000 (45%) |
| December 15 | ₹72,000 | ₹1,80,000 (75%) |
| March 15 | ₹60,000 | ₹2,40,000 (100%) |
There’s a small margin built in. No interest is charged for the first two dates if you’ve paid at least 12% by June 15 and at least 36% by September 15. The December and March targets have no such margin.
The Presumptive Taxation Escape Hatch
If you’re a freelancer or small business owner eligible for presumptive taxation, formerly Section 44ADA (professionals with gross receipts up to ₹75 lakh, if at least 95% of receipts are digital) or Section 44AD (businesses), and now consolidated in Section 58 of the Income-tax Act, 2025, there’s a genuine relief: you’re allowed to pay 100% of your advance tax in a single installment by March 15, with no interest charged for the earlier quarters you skipped. In the example above, the same freelancer under presumptive taxation would owe zero interest, saving the full ₹9,720 — legally, just by using the correct scheme.
The Other Interest You Need to Watch: Section 424 (formerly 234B)
Section 425/234C interest is about missing individual quarterly milestones. Section 424/234B is different — it applies if your total advance tax paid by March 31 is less than 90% of your final assessed tax for the year. Interest here runs at 1% per month from April 1 onward, until you pay the balance as self-assessment tax while filing your return. This one catches people who underestimate their income for the year — a good freelancing year in the last quarter can leave you short even if you paid on time earlier.
Worked example: when income turns out higher than estimated
Go back to the freelancer who estimated ₹2,40,000 of tax and paid every instalment on time. Then a big project lands in February, and the final tax for the year (after TDS) comes to ₹3,00,000. The ₹60,000 balance is paid as self-assessment tax on 20 July, when the return is filed.
- Section 425 (formerly 234C): instalments are now measured against ₹3,00,000. By June 15, ₹36,000 is exactly 12%, and by September 15, ₹1,08,000 is exactly 36%, so the margin covers both. By December 15, the shortfall is ₹45,000 (75% of ₹3,00,000 is ₹2,25,000, minus ₹1,80,000 paid), which costs ₹1,350 for three months. By March 15, the shortfall is ₹60,000, which costs ₹600 for one month.
- Section 424 (formerly 234B): advance tax paid, ₹2,40,000, is only 80% of the ₹3,00,000 due, below the 90% mark. Interest runs on ₹60,000 at 1% a month from April to July, with a part month counting as a full month. That’s four months, or ₹2,400.
Total interest: ₹4,350. Had the freelancer paid the extra ₹60,000 by March 31, it would have counted as advance tax. The Section 424 interest of ₹2,400 would then have been avoided, leaving only the ₹1,950 under Section 425.
Our Verdict
📋 Our Verdict — Advance Tax for Freelancers 2026
“If you’re a freelancer or business owner with any real tax liability, don’t wait for March. Estimate your year’s income as early as you reasonably can and pay quarterly — even a rough estimate paid on time beats a perfect number paid late. And if you qualify for presumptive taxation under 44ADA or 44AD, use it — it’s one of the few completely legal ways to defer your full payment to March without a single rupee of interest.”
Advance Tax — FAQs
Q: I’m a senior citizen freelancer. Do I still need to pay advance tax?
A: Senior citizens (60 years or above) are exempt from advance tax only if they have no income from business or profession. Since freelance income counts as professional income, this exemption does not apply to you.
Q: What if my income varies a lot month to month — how do I estimate it for June?
A: Use your best reasonable estimate based on the year so far and past years’ patterns. You can revise your estimate and adjust the amount at each subsequent installment (September, December, March) as your actual income becomes clearer.
Q: Does TDS deducted by my clients count toward my advance tax obligation?
A: Yes. Your advance tax liability is calculated on your estimated tax minus TDS/TCS already deducted or expected to be deducted during the year — you only need to pay the balance.
Q: Are the old section numbers 234B and 234C still valid anywhere?
A: For FY 2025-26 and earlier returns, the old numbers under the Income Tax Act, 1961 still apply. From FY 2026-27 onward, use the new numbers — 424 and 425 — under the Income Tax Act, 2025.
To estimate your own liability, try our Tax and Loan Calculators, or browse more Tax & Compliance coverage on BadaBanker.
📎 Sources: Income Tax Department: FAQs on interest under Sections 423 to 426, Income-tax Act, 2025; Income Tax Department e-filing portal: advance tax payment and presumptive taxation. For informational purposes only — always verify your specific liability with a qualified Chartered Accountant.
The example showing Rs 9,720 of avoidable interest for paying the same Rs 2,40,000 late really drives home why the four instalments matter. I also found the distinction between the quarterly shortfall interest and the 90 percent rule under the new section 424 very useful, especially for years when income turns out higher than estimated. The presumptive taxation single-payment option is a helpful alternative for eligible freelancers to check.