Small finance bank FD rates in October 2026 go up to 8.10% a year for regular depositors and 8.50% for senior citizens, about one percentage point more than the best rates at large banks. This page compares the small finance bank FD rates published by Equitas, ESAF, Jana, Ujjivan, Unity, Utkarsh and AU Small Finance Bank, with a calculator to compare maturity amounts and a guide to keeping your money safe within the deposit insurance limit.
Last checked: 18 October 2026, from each bank’s own website. Rates are for deposits below ₹3 crore and change often, so confirm the rate on the bank’s website on the day you book.
Highest small finance bank FD rates, October 2026
Most small finance banks (SFBs) pay their best rate on one special tenure, such as 501, 666, 800 or 888 days. Here is each bank’s highest published rate and the tenure it applies to.
| Bank | Regular | Senior citizen | Tenure | Rates effective |
|---|---|---|---|---|
| Equitas SFB | 8.00% | 8.50% | 3 years 1 day (Maxima FD, 1% penalty if closed early) | 16 June 2026 |
| ESAF SFB | 8.00% | 8.50% | 800 days | 17 August 2026 |
| Jana SFB | 8.00% | 8.30% | Over 2 years to 3 years | 29 September 2026 |
| Ujjivan SFB | 7.80% | 8.30% | 3 years 1 day to 3 years 6 months | 1 September 2026 |
| Unity SFB | 7.80% | 8.30% | 501 days (per rate sheet; website advertises up to 8.5%) | 11 June 2026 |
| Utkarsh SFB | 8.10% | 8.25% | 666 days | 5 May 2026 |
| AU SFB | 7.40% | 7.90% | 30 months 1 day to 36 months | 1 September 2026 |
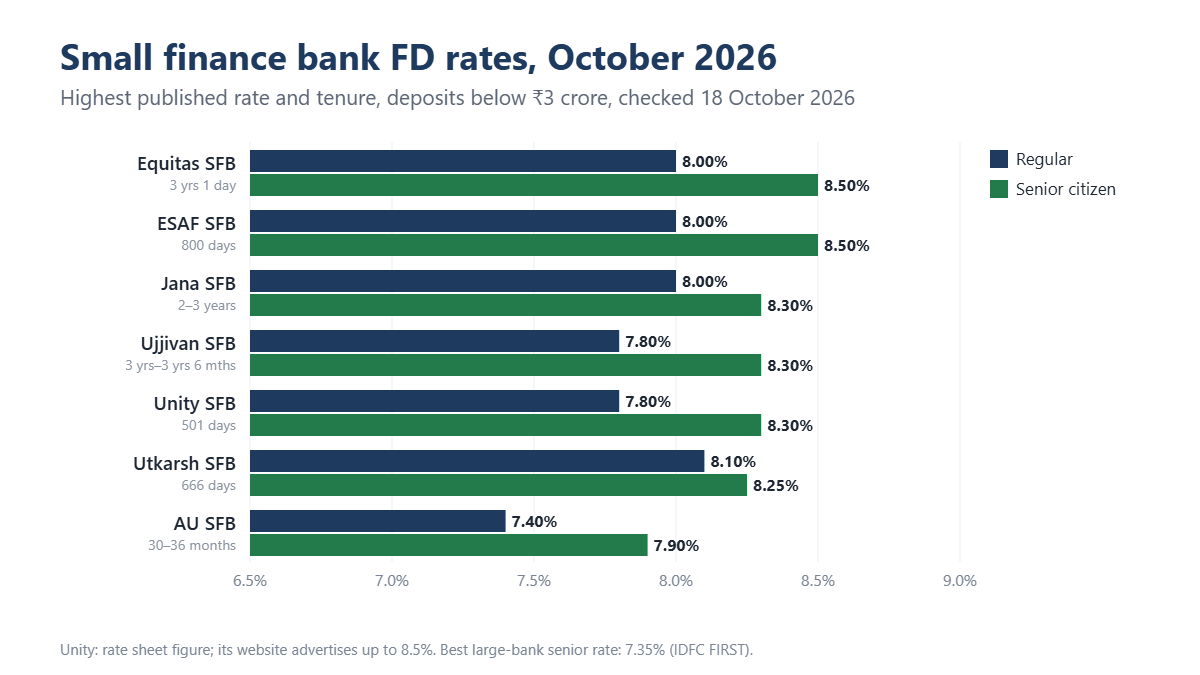
For comparison, the best senior citizen rate at a large bank is 7.35% (IDFC FIRST Bank), and most large banks top out at 7.05% to 7.25%. See our senior citizen FD rates comparison for SBI, HDFC, ICICI and other large banks.
Small finance bank FD rates by tenure
Away from their special tenures, SFB rates can be much lower. ESAF, for example, pays 7.75% for 2 years but 6.00% for exactly 3 years. Rates below are regular / senior citizen, at the exact tenure shown.
| Bank | 1 year | 2 years | 3 years | 5 years |
|---|---|---|---|---|
| Equitas SFB | 7.10 / 7.60 | 7.00 / 7.50 | 7.10 / 7.60 | 7.00 / 7.50 |
| ESAF SFB | 6.00 / 6.50 | 7.75 / 8.25 | 6.00 / 6.50 | 5.75 / 6.25 |
| Jana SFB | 7.00 / 7.50 | 7.30 / 7.80 | 8.00 / 8.30 | 7.77 / 8.00 |
| Ujjivan SFB | 7.25 / 7.75 | 7.55 / 8.05 | 7.25 / 7.75 | 7.20 / 7.70 |
| Unity SFB | 7.50 / 8.00 | 6.75 / 7.25 | 6.75 / 7.25 | 6.75 / 7.25 |
| Utkarsh SFB | 6.00 / 6.50 | 7.50 / 8.00 | 7.50 / 8.00 | 7.00 / 7.50 |
| AU SFB | 6.35 / 6.85 | 7.00 / 7.50 | 7.40 / 7.90 | 6.75 / 7.25 |
Best small finance bank FD rates by tenure: 1 year Unity (7.50% / 8.00%); 2 years ESAF (7.75% / 8.25%); 3 years Jana (8.00% / 8.30%); 5 years Jana (7.77% / 8.00%).
How much more an SFB FD earns: an example
Take ₹4 lakh in a 3-year FD for a regular depositor, with interest compounded quarterly and reinvested:
| Bank (3-year rate) | Maturity amount | Interest earned |
|---|---|---|
| SBI (6.30%) | ₹4,82,505 | ₹82,505 |
| Equitas SFB (7.10%) | ₹4,94,030 | ₹94,030 |
| AU SFB (7.40%) | ₹4,98,416 | ₹98,416 |
| Jana SFB (8.00%) | ₹5,07,297 | ₹1,07,297 |
Jana pays ₹24,792 more than SBI over three years. But its maturity amount of ₹5,07,297 is above the ₹5 lakh DICGC cover, so about ₹7,300 of it would not be insured if the bank failed. A deposit of ₹3.9 lakh keeps the whole maturity amount within the cover.
Who should consider an SFB FD?
- Savers who want a higher fixed return and can keep their total at each bank within ₹5 lakh.
- Senior citizens looking for income, after first using the Senior Citizens Savings Scheme (8.2%, up to ₹30 lakh).
- Not your emergency fund, if the best rate is on a long special tenure that carries a penalty for early withdrawal.
SFB FD calculator
Use this calculator to compare small finance bank FD rates for your amount and tenure. Enter an amount and pick a tenure to see what each bank would pay. Switch on senior citizen rates if you are 60 or older.
Rates at the exact tenure shown, for deposits below ₹3 crore, from each bank’s website as checked on 18 October 2026. Many banks pay more on one special tenure (see the table above). Estimates use simple interest below 6 months and quarterly compounding from 6 months, before tax. Keep each bank’s total, including interest, within the ₹5 lakh DICGC cover.
Are small finance bank FDs safe?
Small finance banks are scheduled banks licensed and regulated by the RBI, and their deposits are covered by the Deposit Insurance and Credit Guarantee Corporation (DICGC), the same as at SBI or HDFC Bank. DICGC insures up to ₹5 lakh per depositor per bank, including interest. Deposits at different branches of the same bank are added together.
Small finance bank FD rates are higher because SFBs are smaller and newer than large banks and need to attract deposits. Most of their lending goes to small borrowers: RBI rules require them to lend 75% of their adjusted net bank credit to priority sectors such as small businesses and farmers. That is why it makes sense to stay within the insurance limit at each SFB.
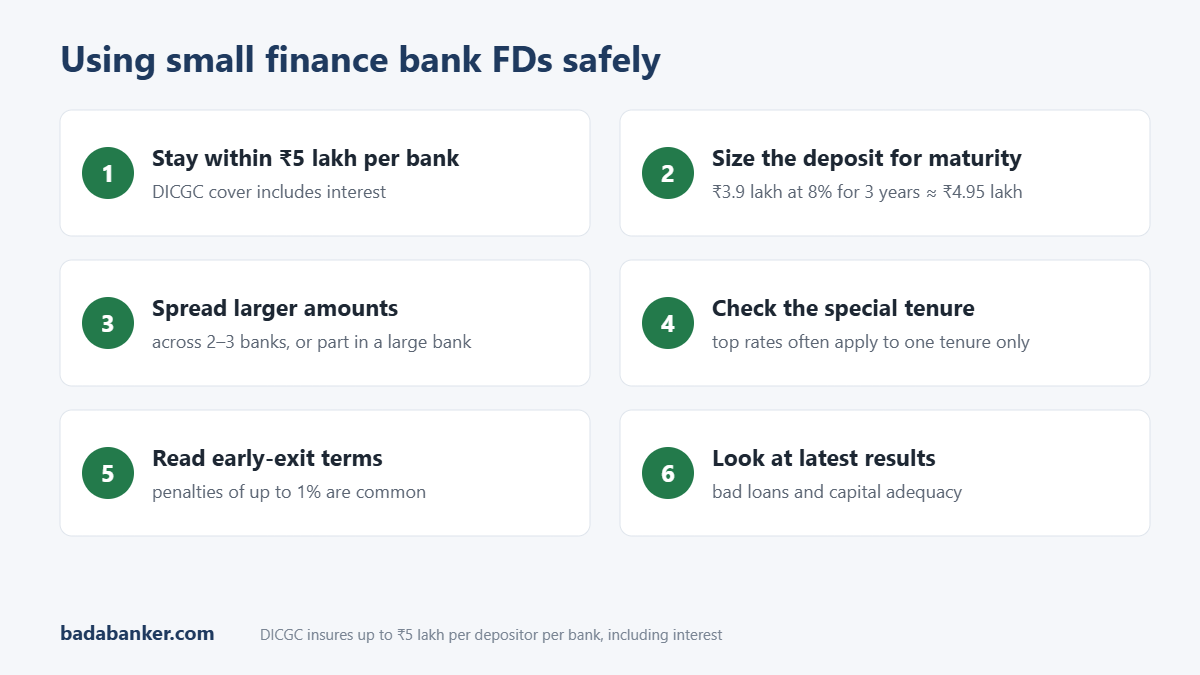
- Stay within ₹5 lakh per bank, counting interest. On a 3-year FD at 8%, a deposit of about ₹3.9 lakh with quarterly compounding grows to roughly ₹4.95 lakh. Keep principal low enough that the maturity amount stays within ₹5 lakh.
- Spread larger amounts across two or three SFBs, or keep part in a large bank.
- Check the special tenure. The headline rate may apply only to one tenure, such as 800 or 888 days.
- Read the early-withdrawal terms. Several SFBs, including Unity and Utkarsh, charge a 1% penalty. Equitas waives it after 6 months on regular FDs but not on its Maxima FD.
- Look at the bank’s latest results. Listed SFBs publish their bad-loan ratio and capital adequacy every quarter.
- Add a nominee to every deposit.
Tax on SFB FD interest
FD interest from an SFB is taxed like interest from any bank. The bank deducts TDS when your interest from that bank in a financial year exceeds ₹50,000, or ₹1 lakh for senior citizens. From 1 April 2026, if the tax on your total income will be nil, submit Form 121 (which replaced Forms 15G and 15H) at the start of the year. Read more in our guide to TDS on FD interest.
Frequently asked questions
Which small finance bank has the highest FD rate?
For regular depositors, Utkarsh SFB at 8.10% for 666 days. For senior citizens, Equitas SFB (8.50% on its 3 years 1 day Maxima FD) and ESAF SFB (8.50% for 800 days), as of 18 October 2026.
Are small finance bank FDs insured?
Yes. DICGC insures deposits at all SFBs up to ₹5 lakh per depositor per bank, and that limit includes interest.
Why are small finance bank FD rates higher than big banks?
SFBs are smaller and newer, so they pay more to attract deposits. They also lend mainly to small borrowers, which earns them higher interest but carries more risk than a large bank’s loan book.
Will small finance bank FD rates rise after the repo hike?
Possibly. The RBI raised the repo rate to 5.50% on 7 October 2026, and banks often raise deposit rates after a hike, but each bank decides for itself. Jana’s retail rates are the most recent in this list (29 September 2026). We will update this page as banks revise their rates.
Should I choose an SFB FD or a mutual fund?
They do different jobs. An FD gives a fixed, known return and suits money you need within a few years. Equity mutual funds can earn more over long periods but their value goes up and down. Many people keep both: FDs for safety and near-term goals, and funds for long-term growth.
Related reading
Sources
- Equitas SFB, Fixed deposit interest rates (effective 16 June 2026)
- ESAF SFB, Interest rates (effective 17 August 2026)
- Jana SFB, Interest rates (retail FD effective 29 September 2026)
- Ujjivan SFB, Latest fixed deposit interest rates (effective 1 September 2026)
- Unity SFB, Fixed deposit page and linked rate sheet (revised 11 June 2026)
- Utkarsh SFB, Fixed deposit rates on its Digital FD page (effective 5 May 2026)
- AU SFB, Fixed deposit interest rates (effective 1 September 2026)
- DICGC, A guide to deposit insurance
- Income Tax Department, Form No. 121
Rates are as published by each bank on the date checked, for resident individuals and deposits below ₹3 crore. Banks can change rates without notice. BadaBanker is not a deposit agent and this is general information, not investment advice.