A common situation: a shop owner applies for a ₹20 lakh personal loan to expand, without realising that a flat they already own could secure the same amount at a noticeably lower rate. This mix-up is common — people default to personal loans because they’re faster, without checking what a Loan Against Property (LAP) would actually cost them over the life of the loan.
Let me break down the real numbers so you can see exactly what the difference is worth.
Quick Fact Check — LAP vs Personal Loan 2026
- Loan Against Property rates: typically 9%-14% per annum — lower because your property secures the loan.
- Personal loan rates: typically 10.5%-24% per annum — higher because the loan is unsecured, so the bank takes on more risk.
- LAP amounts can go much higher (often ₹50 lakh to several crores, based on property value) while personal loans are usually capped lower for most salaried borrowers.
- Personal loans disburse faster — often within 1-3 days — while LAP typically takes 2-4 weeks due to property valuation and legal checks.
9%-14%
Loan Against Property interest rate range
10.5%-24%
Personal loan interest rate range
1-3 Days
Personal loan disbursal time
2-4 Weeks
LAP disbursal time (valuation + legal check)

The Real Numbers: ₹20 Lakh Over 5 Years
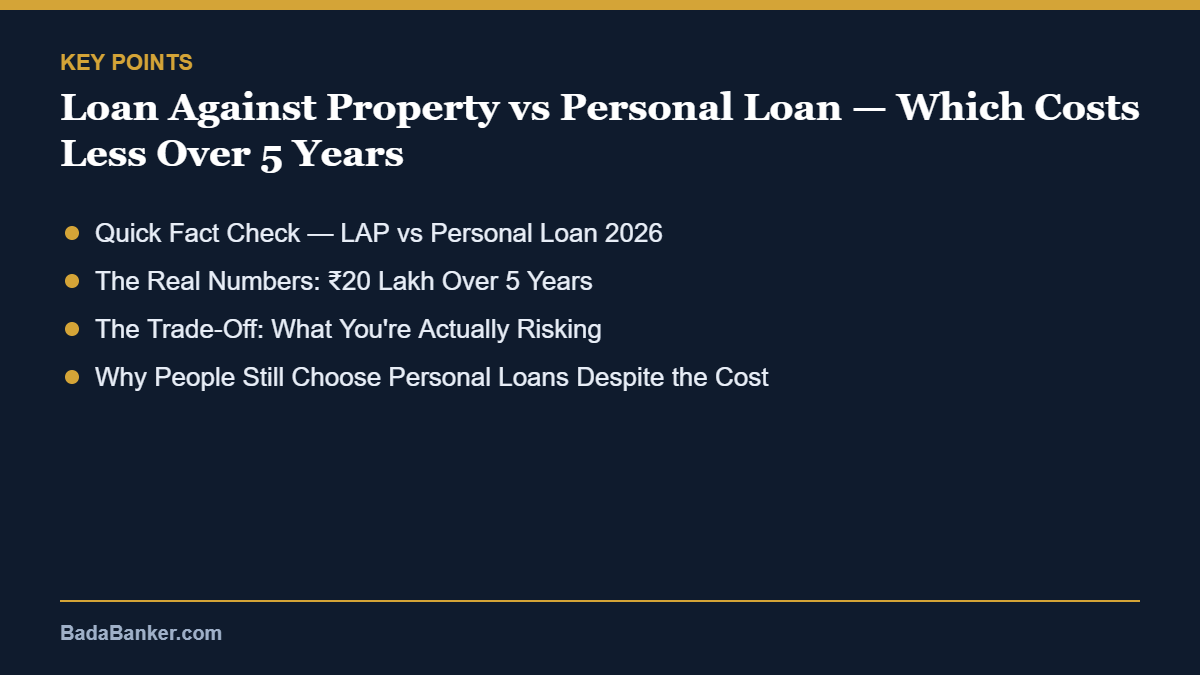
Here’s the actual cost difference for a ₹20 lakh loan over a 5-year tenure, comparing a representative LAP rate of 10% against a representative personal loan rate of 14% — both realistic for a borrower with a good, but not exceptional, credit profile.
| Loan Against Property (10%) | Personal Loan (14%) | |
|---|---|---|
| Monthly EMI | ≈ ₹42,490 | ≈ ₹46,540 |
| Total amount paid over 5 years | ≈ ₹25,49,000 | ≈ ₹27,92,000 |
| Total interest paid | ≈ ₹5,49,000 | ≈ ₹7,92,000 |
| Extra cost of personal loan | ≈ ₹2,43,000 more over 5 years | |
Archana’s Tip: That ₹2.43 lakh difference is real money for essentially the same loan amount and tenure. If you own unencumbered property and need a large sum for a legitimate purpose — business expansion, a child’s education, medical costs — a LAP is almost always the cheaper option, provided you’re comfortable with the trade-off explained below.
The Trade-Off: What You’re Actually Risking
The lower rate on a LAP isn’t free — you’re putting your property up as collateral. If you default, the bank has the legal right to eventually take possession of and sell that property to recover its dues. A personal loan default is serious too (it wrecks your credit score and invites legal recovery action), but it doesn’t put a specific, named asset at direct risk. This is the real question to ask yourself: how confident are you in your ability to service this loan for its full tenure?
Why People Still Choose Personal Loans Despite the Cost
Speed and simplicity. If you need money urgently — a medical emergency, a narrow business opportunity — waiting 2-4 weeks for property valuation and legal verification isn’t practical. Personal loans also don’t require you to own property at all, which is the deciding factor for many younger borrowers. The higher rate is effectively the price of speed and not needing collateral.
Other Costs to Compare
The interest rate is the biggest difference, but it is not the only cost. Before you decide, ask each lender for its Key Fact Statement and compare:
- Processing fee: charged on both loans, usually as a percentage of the loan amount.
- LAP-only costs: property valuation, legal verification of the title and, in many states, stamp duty on the mortgage document. These can add a meaningful amount to a LAP’s upfront cost.
- How much you can borrow: a LAP is limited to a percentage of the property’s value set by each lender, so the amount you get may be lower than the property’s market price.
Prepayment: a 2026 change in your favour
Under the RBI’s Pre-payment Charges on Loans Directions, 2025, for floating-rate loans sanctioned or renewed on or after January 1, 2026:
- lenders cannot charge any prepayment fee on loans to individuals for purposes other than business;
- for business loans to individuals and micro and small enterprises, commercial banks cannot charge one at all, and small finance banks, regional rural banks and mid-sized NBFCs cannot charge one on loans up to ₹50 lakh;
- this applies to part and full prepayment, whatever the source of the money, with no minimum lock-in period.
So if you take a floating-rate LAP and later want to repay early from business profits or a property sale, check whether these rules cover your loan. Fixed-rate loans are not covered, and charges on them follow the lender’s own policy.
A Tax Detail Most People Miss
Under the old tax regime, home loan interest gets a deduction under Section 24(b), but that specifically applies to loans taken to purchase or construct the mortgaged property — not to a LAP used for business or personal expenses. However, if you can demonstrate the LAP funds were genuinely used for business purposes, the interest may be claimable as a business expense against your business income.
A personal loan’s interest is generally not tax-deductible at all, unless similarly used and documented for business or for home construction/improvement. Don’t assume either loan gives you a tax break by default — check with a CA based on actual fund usage.
Our Verdict
📋 Our Verdict — LAP vs Personal Loan 2026
“If you own property and can tolerate the 2-4 week processing time, a Loan Against Property will almost always cost significantly less over the loan’s life — in our example, about 30% less in total interest for the same amount. Choose a personal loan only when you genuinely need speed, don’t own qualifying property, or the loan amount is small enough that the rate difference doesn’t matter much in absolute terms.”
LAP vs Personal Loan — FAQs
Q: Can I get a Loan Against Property on a property that already has a home loan on it?
A: Yes, in many cases — you can get a LAP on the unencumbered value of the property (its current value minus the outstanding home loan), though terms vary by lender.
Q: What happens to my LAP if I sell the mortgaged property?
A: You’ll need to close the LAP (typically using part of the sale proceeds) before the property’s title can be transferred free of the bank’s lien.
Q: Is a Loan Against Property only available on residential property?
A: No, most lenders offer LAP against residential, commercial, and sometimes industrial property, subject to their specific valuation and eligibility criteria.
Q: Which loan is easier to get with a lower credit score?
A: LAP applications are somewhat more forgiving of a modest credit score because the property collateral reduces the lender’s risk, whereas personal loan approval and pricing are heavily dependent on your credit score alone.
To compare your own numbers, try our Loan Calculators, or browse more Loans coverage on BadaBanker.
📎 Sources: RBI — Pre-payment Charges on Loans Directions, 2025; industry-reported interest rate ranges for Loan Against Property and Personal Loans, 2026; Income Tax Department guidance on Section 24(b) and business expense deductions. For informational purposes only — actual rates depend on your lender, credit profile, and property valuation.
The ₹20 lakh worked example makes the trade-off concrete: saving about ₹2.43 lakh in interest over five years is hard to ignore, but it comes with the risk of pledging a property. I found the section on the 2026 prepayment change especially useful, because early repayment was often where borrowers were caught out. For a shop owner who can wait two to four weeks, the secured route clearly deserves a proper comparison before signing.