For a specific 3-year goal — a wedding, a down payment, a planned purchase — clients often ask about RD vs FD: which one to save in. The honest answer depends on whether you already have the lump sum or need to build it up.
In short: the RD vs FD choice for a 3-year goal depends on whether you have a lump sum today or will save every month. The sections below set out the RD vs FD trade-offs for a 3-year goal.
Quick Fact Check — RD vs FD for 3 Years
- FD (Fixed Deposit): You invest a lump sum upfront; ideal if you already have the money and want it to grow with a locked-in rate.
- RD (Recurring Deposit): You invest a fixed amount monthly; ideal if you’re building savings gradually rather than starting with a lump sum.
- Interest rates are typically similar in the RD vs FD choice at the same bank for the same tenure — the real difference is about your savings pattern, not the rate itself.
- Interest is taxable: FD and RD interest is generally included in taxable income. For resident depositors, the relevant bank time-deposit TDS threshold is ₹50,000 per year, or ₹1,00,000 for senior citizens. These are deduction thresholds, not tax exemptions; eligible declarations and other exceptions can affect deduction.
Similar Rates
In the RD vs FD comparison, rates are usually comparable
Lump Sum
FD is best if you have it upfront
Monthly Savings
RD is best if you are building the amount

The Real Decision Factor: What You Have Today
If you already have ₹3 lakh sitting in your savings account for a 3-year goal, an FD locks in today’s rate on the full amount immediately — waiting and drip-feeding it into an RD instead would mean most of your money earns less for longer. If you don’t have the lump sum and need to save ₹8,000/month to reach a similar goal, an RD forces disciplined monthly saving with a bank-guaranteed return, which beats leaving it in a low-interest savings account.
Worked example: same goal, two ways to save
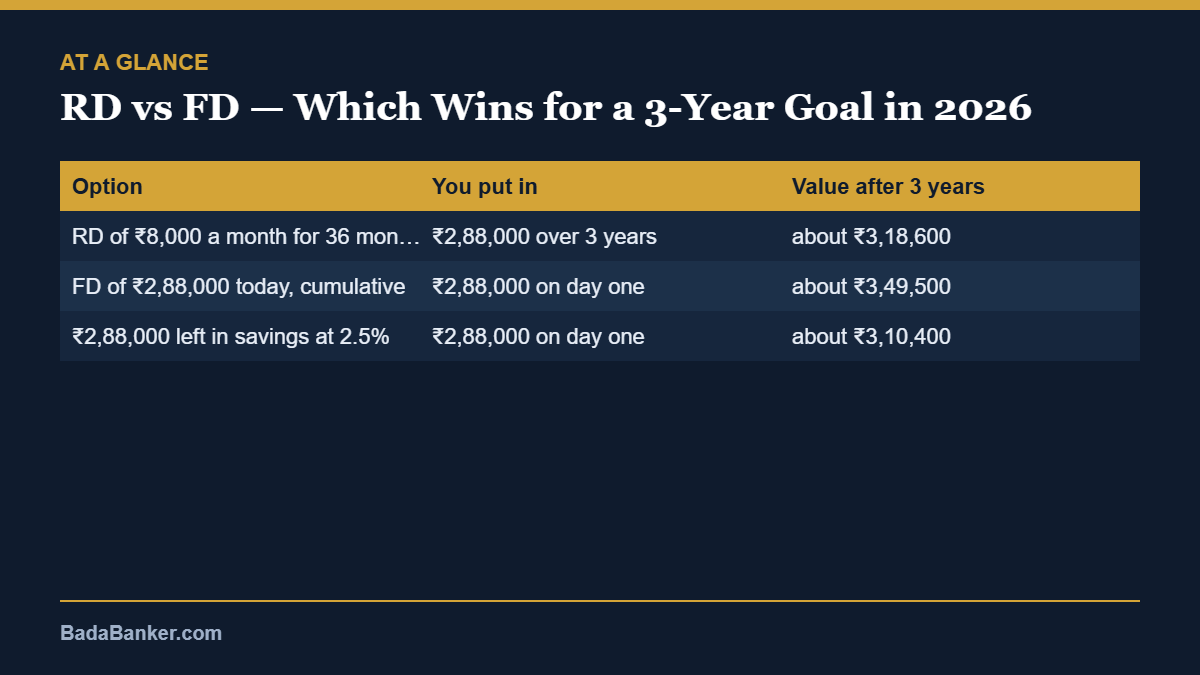
Take a 3-year deposit rate of 6.5% a year, compounded quarterly as most banks do. This rate is for illustration only, so use your bank’s current rate.
| Option | You put in | Value after 3 years | Interest earned |
|---|---|---|---|
| RD of ₹8,000 a month for 36 months | ₹2,88,000 over 3 years | about ₹3,18,600 | about ₹30,600 |
| FD of ₹2,88,000 today, cumulative | ₹2,88,000 on day one | about ₹3,49,500 | about ₹61,500 |
| ₹2,88,000 left in savings at 2.5% | ₹2,88,000 on day one | about ₹3,10,400 | about ₹22,400 |
The FD earns about twice the interest of the RD. That isn’t because the rate is better: the whole amount earns interest for the full three years, while each RD instalment earns only for the months left after it is paid. So on RD vs FD, if you already have the money, an FD wins clearly. If you don’t, an RD is the right tool, and about ₹9,040 a month at 6.5% would build roughly ₹3,60,000 in three years.
Tax: the interest is added to your income each year and taxed at your slab rate. At a 30% slab, plus cess, the RD’s roughly ₹30,600 of interest would cost about ₹9,500 in tax over the three years. TDS applies only if your interest from the bank crosses the threshold in a year.
Archana’s Tip: If you have part of the amount already and expect to add more monthly, consider a combination — put the lump sum in an FD now, and start an RD for future monthly savings. There’s no rule that says you must choose only one.
Which FD Type Should You Choose?
Not all FDs are the same. A cumulative FD reinvests interest and pays it all at maturity — best for a 3-year goal since you get the full compounding benefit and don’t need periodic income. A non-cumulative FD pays interest monthly/quarterly — better if you need regular income, but works against you here since the point of a 3-year goal is to let the full amount grow. For a goal-based 3-year FD, always choose cumulative unless you specifically need the interim payouts.
A Simple Laddering Trick
If you’re not 100% sure you’ll need the full amount exactly at the 3-year mark, split your lump sum across 2-3 FDs with staggered maturities (e.g., 30/33/36 months) instead of one single FD. This way, if your goal shifts earlier, you’re not breaking your entire deposit and losing interest on the whole amount — only on any deposit you actually close before its agreed maturity. A deposit that matures normally does not incur a premature-closure penalty.
What breaking a deposit early costs
Banks usually pay the rate that applied to the period the deposit actually ran, minus a penalty, often 0.5% to 1%. For example, if you break a ₹3,00,000 FD after two years, your bank’s two-year rate is 6.4% and the penalty is 1%, you’d get 5.4% for two years: about ₹3,34,000 instead of about ₹3,41,300 at the full 6.5%. That’s a loss of roughly ₹7,300. Penalties vary by bank and product, so read the premature withdrawal clause before you open the deposit.
Our Verdict
📋 Our Verdict — RD vs FD for a 3-Year Goal
“This isn’t really an FD-vs-RD rate question — it’s a ‘what do I have today’ question. Lump sum in hand: choose FD. Building up gradually: choose RD. Compare the bank, deposit protection, tax and withdrawal conditions as well as the interest rate.”
RD vs FD — FAQs
Q: Can I break an FD or RD early if my goal changes?
A: Yes, both allow premature withdrawal, typically with a penalty (reduced interest rate) — RDs sometimes have stricter penalty terms than FDs, so check your bank’s specific policy.
Q: Do senior citizens get a better rate on RD or FD?
A: Both typically offer a similar additional rate (commonly 0.25%-0.50% higher) for senior citizens on either product.
Q: What’s the difference between a tax-saver FD and a regular FD?
A: A 5-year tax-saver FD qualifies for a deduction of up to ₹1.5 lakh, but only if you file under the old tax regime. It has a mandatory 5-year lock-in with no premature withdrawal, so it doesn’t suit a 3-year goal.
Q: Can I take a loan against my FD/RD instead of breaking it?
A: Yes — most banks offer a loan/overdraft against FD (typically up to 90-95% of the deposit value) at a small markup over the FD rate, but compare the borrowing cost for the time you need the money against the premature-withdrawal cost; neither is always cheaper.
Q: Does nomination matter for a 3-year FD/RD?
A: Yes — always add a nominee regardless of tenure; it has no downside and simplifies claims in any unforeseen event.
To compare exact numbers for your goal, try our FD calculator and RD calculator, or browse more Fixed Deposits coverage on BadaBanker.
Whichever you pick in the RD vs FD decision, compare the bank’s current rates and read its premature withdrawal terms before you open the deposit.
Related reading
Sources and verification
- Income Tax Department: TDS threshold limits.
- Income Tax Department: TDS transition FAQs — rates and thresholds remain unchanged under the new Act.
- DICGC: deposit insurance guide — eligible principal and interest are combined for the ₹5 lakh limit per depositor per bank in the same right and capacity.
Check the selected bank’s current product terms for rates, instalment timing, senior-citizen eligibility and early-withdrawal rules. Educational information only.
Framing this as a “what do I have today” question, rather than a rate comparison, is exactly right. The worked example showing about ₹61,500 from an FD against about ₹30,600 from an RD on the same ₹2,88,000 explains why timing matters more than the headline rate. The laddering tip is also a sensible middle path for anyone unsure whether they will need the money exactly at three years.